


Right Now

Global Industrial Bypass Switches Market: Strategic Shifts and Commercial Opportunities Through 2032
The global industrial bypass switches market is entering a decisive expansion phase, shaped by rising power reliability demands, stricter compliance requirements, and structural shifts in industrial architecture. From 2020 through 2025, the market demonstrated steady growth, accelerating into 2026 and beyond as digitalization, critical infrastructure protection, and renewable integration intensify. Over the 2026–2032 forecast horizon, the sector is projected to expand at a compound annual growth rate of 5.5 percent, reflecting sustained capital deployment across manufacturing, power distribution, and mission-critical facilities. With the market reaching an estimated 175.5 million in 2025 and climbing toward higher thresholds by the end of the decade, the trajectory signals more than incremental demand growth—it reflects a fundamental rethinking of how power continuity, isolation, and maintenance are engineered into modern industrial systems.
Behind the headline growth numbers lie structural tensions that will define competitive positioning in the coming years. Supply chain volatility, material cost pressures, and evolving regulatory expectations are forcing manufacturers and end users to recalibrate sourcing strategies and product architectures. At the same time, demand is fragmenting across use cases: some environments prioritize fast, automated isolation for continuous operations, while others require manual, serviceable bypass solutions for cost-sensitive or space-constrained installations. Navigating these dynamics requires more than tracking market size; it demands an understanding of how technology roadmaps, compliance frameworks, and procurement behavior intersect to create pockets of durable margin and differentiated value.
Current Market Landscape and Core Challenges
The market’s expansion is anchored by broad-based demand for power continuity, but growth is uneven across application profiles and regional deployment patterns. Industrial facilities, data infrastructure, power utilities, and energy-intensive processing sectors all contribute to pull, yet each exposes operators to distinct operational constraints. The overall market size has scaled consistently over the past half-decade, and the forward trajectory suggests continued investment as organizations treat bypass and isolation switching as core components of resilience rather than optional add-ons. However, the pace of adoption is moderated by several concurrent challenges.
First, material and component cost volatility is reshaping cost structures. Conductive metals remain the dominant choice for switch conductors globally, but rising input prices and semiconductor-related expenses have introduced procurement friction. Manufacturers are navigating tighter margins while end users face longer evaluation cycles as procurement teams stress-test total cost of ownership against reliability requirements. This environment rewards suppliers that can balance performance, compliance, and transparent cost positioning, while pressuring those reliant on commodity-driven pricing models.
Second, regulatory and testing expectations are becoming a gating factor in mission-critical deployments. Standards governing closing speed, withstand ratings, and safe isolation during maintenance are increasingly central to specification decisions in healthcare, pharmaceutical, and industrial settings. Equipment that can demonstrate validated performance under these requirements is gaining preference, while non-compliant or less rigorously tested designs face longer qualification cycles and greater specification risk. Compliance is no longer a baseline checkbox; it is a competitive differentiator in segments where downtime translates directly into operational and financial exposure.
Third, the market is experiencing a divergence between performance density and serviceability. Automation and fast-switching designs reduce transition times and support uninterrupted maintenance workflows, but they also introduce integration complexity and higher upfront engineering demands. Conversely, simpler manual configurations remain relevant for cost-sensitive applications, yet their adoption is constrained by growing expectations for operational continuity. Suppliers must therefore manage a wider design spectrum without diluting their value proposition, while customers must balance capital expenditure, maintenance strategy, and operational risk in a more nuanced way.
Key Demand Drivers Reshaping the Market
Several forces are converging to accelerate adoption and reshape how bypass switch solutions are specified, deployed, and maintained. These drivers are not isolated; they reinforce one another and create compounding opportunity for organizations that align product strategy, service models, and supply chain resilience with emerging expectations.
DIP Switches Market
Technology innovation and switching performance. Advances in contact design, actuation speed, and isolation architecture are expanding the range of environments where bypass switches can be deployed safely and efficiently. High-speed switching capabilities are especially relevant for applications requiring rapid source transfer, fault protection, and maintenance without service interruption. Products engineered for fail-safe behavior, validated cycling performance, and compact footprints are gaining traction in mission-critical facilities, where space constraints and reliability requirements intersect. Innovations that combine motorization, automatic transfer, and manual bypass flexibility are enabling users to maintain operational continuity while simplifying maintenance tasks.
Policy, standards, and compliance-driven specification. Regulatory expectations are increasingly shaping purchasing decisions, particularly in sectors where downtime carries high consequences. Testing frameworks that verify withstand ratings, closing performance, and safe isolation during maintenance are becoming central to specification language. As these standards become more widely referenced in procurement processes, suppliers with documented compliance and application-specific validation are positioned to shorten evaluation cycles and reduce specification risk for end users. This trend also raises the barrier for untested or generic offerings in high-stakes deployments.
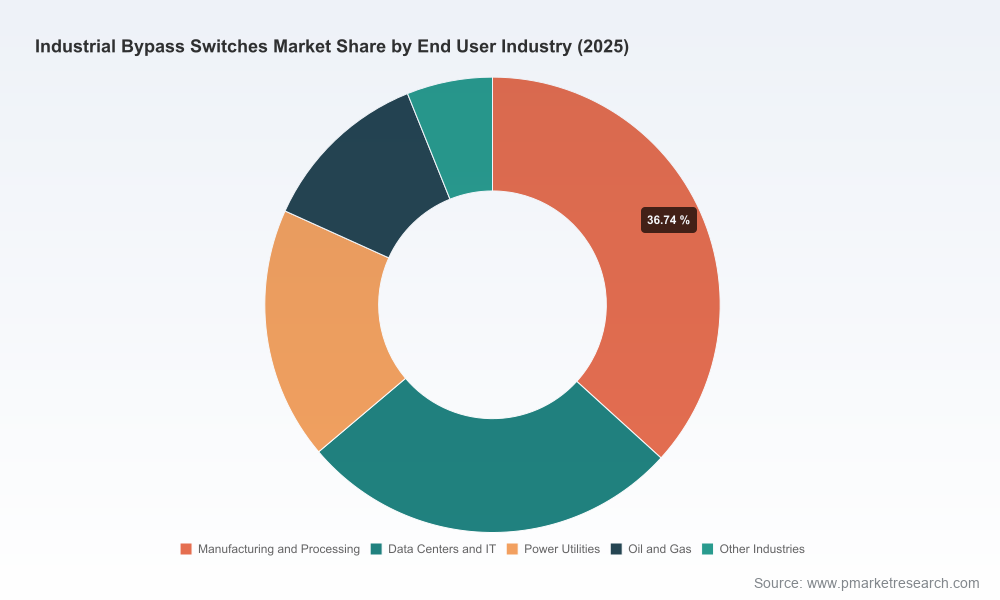
Demand-side shifts toward uptime, automation, and energy resilience. Industrial operators, data infrastructure owners, and utility stakeholders are prioritizing power continuity and predictable maintenance windows. The push for automation is reducing reliance on manual intervention during transitions and maintenance, while rising awareness of energy efficiency and renewable integration is broadening the use of bypass and isolation solutions in hybrid power architectures. In parallel, sectors such as manufacturing and processing continue to expand operational complexity, increasing the need for switchgear that can manage load transfer, isolation, and serviceability without disrupting production schedules.
Supply chain and cost-structure recalibration. Material availability and pricing dynamics are influencing both product design and purchasing strategy. Procurement teams are paying closer attention to conductor selection, component durability, and lifecycle cost rather than first-price alone. At the same time, suppliers are adjusting sourcing strategies, design choices, and inventory planning to manage exposure to metal price fluctuations and component constraints. These adjustments are gradually reshaping competitive dynamics, favoring organizations that can demonstrate supply discipline and design flexibility while maintaining performance benchmarks.
Competitive Landscape and Leading Strategies
The competitive field is shaped by a mix of large multinational suppliers and specialized manufacturers, each pursuing distinct positioning based on application focus, switching performance, compliance emphasis, and integration capabilities. Rather than competing solely on scale, leading companies are differentiating through design philosophy, validation depth, and proximity to specific operational requirements.
One clear pattern is the bifurcation between broad industrial power distribution portfolios and highly specialized high-performance bypass solutions. Larger players tend to emphasize wide product ranges, integration with transfer switching, and applicability across data centers, utility infrastructure, and general industrial environments. Their advantage lies in breadth, global distribution, and the ability to address multiple segments with common platforms. At the same time, more specialized suppliers focus on ultra-fast actuation, high-current handling, and protection-oriented designs for demanding electrical architectures. In those niches, value is created through switching speed, durability, and application-specific engineering rather than portfolio size alone.
Another strategic axis is compliance and mission-critical validation. Suppliers that highlight tested performance under recognized standards and fail-safe maintenance designs are building trust in sectors where specification risk is high and downtime consequences are severe. This approach is particularly visible in healthcare, pharmaceutical, and other critical industrial facilities, where safe isolation and maintenance bypass capabilities are closely tied to operational continuity. These offerings are not just hardware; they are positioned as risk-reduction solutions that simplify compliance and maintenance planning.
A third dynamic is the growing relevance of applied integration. Some manufacturers emphasize pre-configured designs, space-saving construction, and integration with broader power distribution or generation systems. Others highlight modular actuation, varied pole configurations, and flexibility for motor drives and infrastructure circuits. The common thread is a move toward solutions that reduce engineering burden at the installation stage while supporting long-term serviceability. This shift matters because specification teams increasingly favor equipment that aligns with both immediate deployment constraints and future maintenance workflows.
Recent activity illustrates how these strategies are being communicated and refined. A major supplier highlighted automatic transfer switch series with bypass and isolation capability, including fail-safe designs and maintenance bypass configurations validated against recognized cycling requirements for mission-critical applications. This kind of messaging reinforces the market’s shift toward documented reliability and maintenance safety as purchasing criteria. Separately, another participant showcased industrial networking and bypass-related products at a major electronics and automation exhibition, signaling continued attention to connectivity, automation, and industrial communication ecosystems. These developments suggest that competition is increasingly played out at the intersection of hardware performance, application validation, and ecosystem awareness.
Looking forward, the competitive landscape is likely to experience both consolidation and specialization. Larger portfolios and cross-segment capabilities will remain valuable, but they will need to be supported by clear application-specific advantages and credible compliance positioning. At the same time, new entrants and niche specialists may carve out roles in high-performance, high-power, or automation-integrated segments where speed, protection, and integration matter more than broad coverage. The result is a market in which scale alone is insufficient; differentiation will depend on how effectively suppliers translate technical capability into measurable operational value.
Bypass Filter Market
Future Trends and Commercial Implications
The next three to five years will likely be defined by a few reinforcing trends that shape both product direction and commercial opportunity. These trends are not speculative; they are already visible in specification behavior, recent product emphasis, and procurement priorities across key industries.
Performance-validated reliability becomes a default expectation. As mission-critical deployments expand and downtime costs rise, validation and testing documentation will matter more in specification decisions. Suppliers that can clearly demonstrate compliance with recognized standards, consistent cycling behavior, and safe maintenance isolation will gain preference in high-stakes environments. The commercial implication is clear: reliability messaging must be supported by verifiable design claims, and procurement strategies that rely on generic performance assertions will face growing scrutiny.
Automation and serviceability converge in design priorities. Demand for uninterrupted maintenance and faster transition management will continue to push designs toward automatic transfer, manual bypass flexibility, and fail-safe isolation. This convergence creates opportunity for solutions that simplify field service while preserving operational continuity. For suppliers, the strategic question is how to balance actuation complexity, footprint, and cost without sacrificing the maintenance benefits that end users increasingly require.
Material and cost pressures drive smarter sourcing and design choices. With conductor and component costs remaining a significant consideration, both manufacturers and buyers will continue adjusting specifications to balance performance and cost. This may accelerate interest in durable contact materials, efficient conductor layouts, and designs that reduce lifecycle exposure to price fluctuations. The commercial opportunity lies in offering transparent total cost positioning and stable supply planning, especially in segments where procurement teams are actively managing volatility.
Renewable and hybrid power integration broaden application scope. As industrial facilities and utilities incorporate more distributed generation, storage, and hybrid architectures, bypass and isolation switching will be needed in a wider set of configurations. This expansion does not simply increase volume; it introduces new specification requirements around protection coordination, switching speed, and integration with power management systems. Suppliers that can align their offerings with these emerging architectures can access growth beyond traditional industrial switchgear use cases.
PW Consulting
These trends also carry risks. One uncertainty is the pace at which compliance expectations tighten across regions and segments, which could create uneven adoption curves and temporarily favor incumbents with established validation records. Another is the potential for material cost volatility to compress margins or delay project timelines, particularly for buyers balancing reliability goals with budget constraints. Finally, integration complexity may become a barrier if automation and switching performance advances outpace the availability of skilled installation and maintenance resources. Organizations that ignore these frictions risk overpromising on capability while underestimating deployment and lifecycle realities.
Strategic Recommendations for Decision-Makers
For manufacturers, the priority is to align product roadmaps with the converging needs of performance, compliance, and serviceability. This means investing not only in switching speed and current-handling capability, but also in documented validation, fail-safe isolation, and designs that support maintenance without interruption. Differentiation will increasingly come from clear application fit and provable reliability rather than broad portfolio claims. Companies should also strengthen supply and cost planning for conductive metals and key components, since procurement resilience will influence both pricing stability and customer confidence. Where possible, offering lifecycle-transparent solutions and service-friendly configurations can help protect margin while meeting the operational expectations of critical environments.
For investors, the most compelling opportunity lies in businesses that combine credible technical validation with strong positioning in high-value end markets. Growth will not be evenly distributed; segments where downtime is costly and compliance expectations are high are likely to support more durable demand. When evaluating exposure, it is important to assess whether a company’s differentiation rests on defensible engineering, recognized performance standards, and integration with mission-critical workflows, or whether it depends primarily on scale and commodity pricing. Suppliers that can navigate material volatility while maintaining performance credibility are better positioned to capture share in a market where specification risk and uptime priorities are both rising.
For procurement and operations leaders, the strategic imperative is to evaluate bypass switch solutions through a broader lens than first-cost or basic functionality. Specification decisions should account for safe isolation during maintenance, cycling validation, switching performance, and compatibility with existing power architecture and automation plans. In environments where continuity matters, selecting equipment with clear maintenance bypass capability and documented testing profiles can reduce operational risk and simplify future service planning. Procurement teams should also engage suppliers early on material sourcing, delivery stability, and lifecycle cost assumptions, since these factors increasingly shape project economics and long-term reliability.
The industrial bypass switches market is moving from steady expansion toward a more competitive, performance-driven, and compliance-sensitive phase. Over the forecast period, success will depend on how well organizations translate technical capability into operational value, manage supply and cost pressures, and align with the way end users now define reliability and maintainability. For decision-makers seeking a clearer view of segment dynamics, regional deployment patterns, and detailed competitive positioning beyond the macro picture, the full research report offers a deeper breakdown of market structure, application demand, and strategic implications tailored to specific investment and procurement decisions.
For detailed analysis of this topic, please visit the official page: Worldwide Industrial Bypass Switches Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
More Posts


Report This Post
Please complete the following requested information to flag this post and report abuse, or offensive content. Your report will be reviewed within 24 hours. We will take appropriate action as described in Findit terms of use.
