


Right Now

Global Laboratory Glass Container Market: Strategic Trends and Commercial Opportunities Through 2032
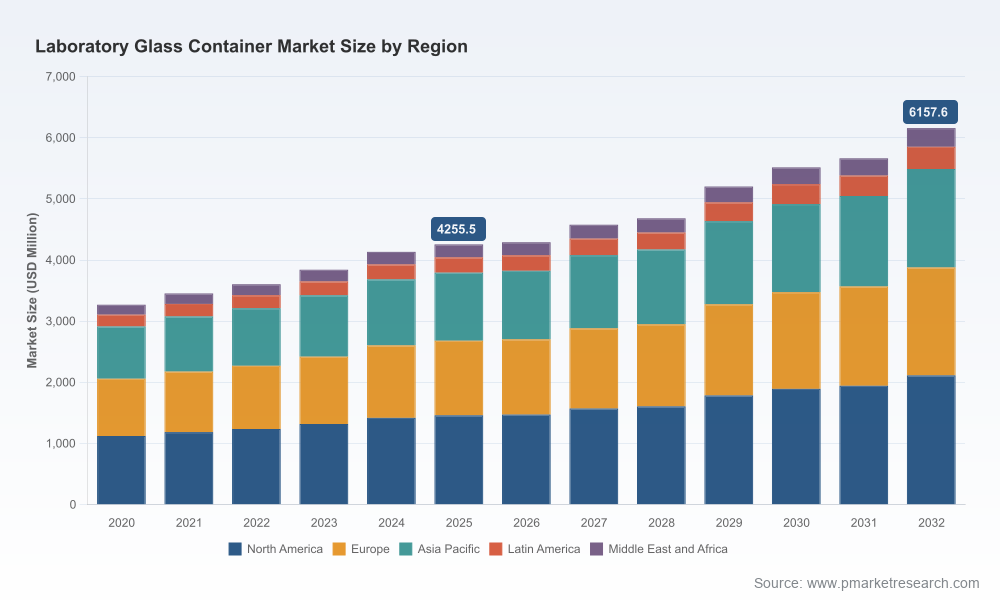
The worldwide laboratory glass container market has entered a phase of steady, structurally driven expansion, reaching approximately 4,255.5 million USD in 2025 and projected to grow at a compound annual growth rate of 5.42 percent through 2032, when revenues are expected to approach 6,157.6 million USD. This trajectory reflects a sector that has matured beyond cyclical commodity dynamics and now operates at the intersection of scientific innovation, regulatory stringency, and supply chain reconfiguration. Over the historical period from 2020 to 2025, the market advanced from roughly 3,268.45 million USD to its current level, demonstrating consistent demand pull even as manufacturers navigated raw material volatility and shifting end-user procurement patterns. Looking ahead, the forecast horizon through 2032 suggests that growth will not be uniform across regions, product categories, or application verticals. Instead, it will be shaped by capital allocation decisions in life sciences, the pace of diagnostic decentralization, and the degree to which suppliers can differentiate through material science and integrated service models.
For executives and investors evaluating this space, the immediate priority is to separate structural tailwinds from temporary demand spikes. Laboratory glass containers are no longer peripheral consumables; they are critical enablers of reproducibility, contamination control, and thermal stability in workflows ranging from early-stage drug discovery to clinical diagnostics and quality assurance. The market’s ongoing evolution rewards players who can anticipate how procurement behavior, material economics, and regulatory expectations will intersect over the next several years. Understanding where scale advantages matter, where customization commands premium pricing, and where geographic demand is shifting will determine which organizations capture margin expansion versus those that merely maintain volume.
Market Dynamics and Structural Challenges
The expansion trajectory of the laboratory glass container market is underpinned by a combination of sustained scientific investment and the replacement of legacy materials with higher-performance alternatives. Borosilicate glass has emerged as the dominant substrate due to its thermal shock resistance, chemical inertness, and dimensional stability, properties that are increasingly non-negotiable in regulated and precision-driven environments. This material preference has compressed the addressable share of lower-cost soda-lime alternatives in critical applications, effectively raising the performance floor for suppliers competing in research, pharmaceutical, and diagnostic segments. At the same time, the market’s breadth across beakers, flasks, bottles, vials, pipettes, test tubes, and petri dishes means that growth is being pulled by different end-use requirements, with primary packaging and precision volumetric formats gaining particular importance as workflows become more standardized and auditable.
Despite the favorable growth outlook, the industry faces a set of structural challenges that will test operational discipline and strategic focus. First, raw material economics are introducing cost pressure that cannot be fully passed through in all segments. Boron compounds and silicate feedstocks have experienced upward price trends, and because borosilicate formulations require precise batching and controlled melting, production expenses are structurally higher than those of commodity glass lines. Suppliers that rely on undifferentiated commodity capacity are increasingly exposed to margin compression unless they offset input costs through scale efficiencies, product mix shifts, or value-added processing. Second, the market is consolidating around a concentrated group of established manufacturers, with the top three players accounting for a notable share and the top five exceeding half of total market value. This concentration creates both stability and friction: incumbents benefit from reputation, certified quality systems, and long-term supply agreements, while smaller producers must navigate higher barriers to entry in regulated channels and struggle to secure shelf space in procurement frameworks dominated by large distributors and institutional buyers.
A third challenge lies in the shifting shape of demand itself. End-user organizations are increasingly scrutinizing total cost of ownership rather than unit price alone, blending considerations of breakage rates, batch consistency, regulatory documentation, and supply reliability into purchasing decisions. At the same time, certain application areas are experiencing workflow redesigns that alter volume and format requirements. Diagnostic decentralization, for example, is expanding testing throughput outside traditional central laboratories, which creates demand for reliable sample containment and handling formats but also intensifies competition from alternative materials where weight, cost, or disposability become decisive. These dynamics mean that growth is available, but it is conditional on suppliers’ ability to align product portfolios with the performance, compliance, and logistics expectations of increasingly sophisticated buyers.
Key Drivers of Market Evolution
Technology innovation continues to be a primary catalyst, but its impact is now visible less in dramatic new product categories and more in the incremental refinement of performance attributes that matter in daily laboratory operations. Advances in forming technology, annealing precision, and surface treatment have improved dimensional consistency, reduced micro-fracture risk, and enhanced compatibility with automated liquid handling and sample tracking systems. In pharmaceutical and biotechnology environments, containers must withstand sterilization regimes, maintain integrity under temperature cycling, and provide reliable barrier properties for sensitive compounds. Suppliers that integrate these performance characteristics with reproducible manufacturing tolerances are able to command stronger positions in high-value workflows, where a single contamination event or measurement deviation can disrupt entire research programs or production batches.
The policy and regulatory environment reinforces the demand for higher-grade glass containers and adds a layer of compliance-driven stickiness to supplier relationships. Analytical and clinical laboratories operate under frameworks that emphasize traceability, validated materials, and documented quality control. In pharmaceutical manufacturing and biopharma processing, primary packaging and intermediate containment must meet stringent criteria for extractables, leachables, and chemical resistance. As inspection regimes and data integrity expectations tighten globally, end-users increasingly favor suppliers that can provide certified documentation, batch-level consistency, and transparent material specifications. This regulatory overlay does not merely constrain choices; it also raises switching costs for buyers, creating durable demand for suppliers that have invested in quality systems and compliance readiness.
Demand-side behavior is shifting as organizations reconfigure how they allocate laboratory resources. The expansion of life science research capacity, ongoing biopharmaceutical pipeline activity, and broader adoption of diagnostic testing are all contributing to sustained consumption of laboratory glass containers. Academic and research institutions continue to be significant users, but commercial laboratories and industrial quality functions are growing their share of demand as companies internalize testing, scale process development, and invest in analytical workflows that support product release and compliance. In parallel, procurement practices are becoming more integrated, with buyers seeking single-source reliability, regional supply resilience, and format standardization across sites. This pattern favors suppliers that can offer broad portfolios, consistent lead times, and the flexibility to accommodate both standardizedhigh-volume orders and specialized custom configurations.
Supply chain and cost structure dynamics are reshaping how value is captured across the market. Manufacturers are increasingly balancing regional production footprints with the need to minimize freight exposure, customs complexity, and lead-time variability. The upward pressure on boron-related input costs has pushed some suppliers to revisit formulation efficiency, energy usage, and scrap reduction, while others are expanding into adjacent product categories that carry higher margins or stronger demand visibility. Notably, recent developments illustrate how companies are responding: one major Indian manufacturer expanded its portfolio beyond traditional glassware into analytical vials, filtration products, instruments, and pharmaceutical primary packaging through acquisitions, signaling a strategic move toward higher-value containment and integrated solutions. Another example involves the expansion of distribution agreements for life science consumables in the U.S. market, highlighting how channel leverage and retail presence can accelerate reach in a fragmented buyer environment. These moves underscore a broader truth: in a market where product performance is increasingly table stakes, differentiation is being pursued through portfolio breadth, channel access, and the ability to serve end-to-end workflow needs.
Competitive Landscape and Leader Strategies
The competitive structure of the laboratory glass container market is characterized by a mix of scaled global manufacturers, specialized incumbent firms, and regional producers that compete on cost, customization, or service proximity. Large multinational players have built their positions on material expertise, broad product catalogs, and established relationships across pharmaceutical, research, and diagnostic channels. Their advantage lies not only in production capacity but in the ability to supply certified, thermally resistant glassware that meets the consistency requirements of regulated environments. Companies with heritage in borosilicate formulations and precision volumetric instruments are particularly well positioned where measurement accuracy, thermal durability, and chemical inertness are directly tied to experimental validity or process compliance.
A distinct strategic layer is added by firms that have deliberately broadened beyond traditional laboratory glassware into adjacent containment, packaging, and instrument-adjacent categories. This expansion reflects an effort to capture more of the value chain, reduce dependence on commodity replacement cycles, and align with end-users who prefer consolidated sourcing for vials, bottles, filtration components, and primary packaging. In life sciences and pharmaceutical contexts, such moves are especially relevant because primary packaging decisions are closely linked to product integrity, regulatory documentation, and supply reliability. Suppliers that can offer integrated options across containers, closure systems, and related consumables reduce friction for buyers and create more defensible relationships over time.
The market is also shaped by regional manufacturers that compete through cost efficiency, rapid delivery, and strong local service networks. In education, general research, and price-sensitive procurement environments, these players can maintain meaningful share by offering reliable standard formats and responsive fulfillment. Their strategic challenge is to avoid commoditization traps while building enough differentiation—through quality assurance, customization capability, or channel partnerships—to protect margins. Meanwhile, family-owned and specialized manufacturers in developed markets often compete on engineering flexibility, custom apparatus design, and long-term customer relationships, serving niches where specification complexity or application uniqueness makes broad-line competition less effective.
Glassware Market
The overall competitive trend points toward selective consolidation and portfolio diversification rather than pure volume competition. Larger players are likely to continue strengthening their positions through capability acquisition, channel expansion, and investment in product lines that carry stronger compliance or performance premiums. At the same time, market fragmentation persists at the regional and application-specific level, creating space for focused competitors that can serve local demand with agility. For buyers, this landscape means that supplier selection is increasingly a function of fit across performance, compliance, logistics, and total cost rather than a simple comparison of unit prices. For suppliers, the strategic question is whether to compete as a broad-line scale provider, a specialized solutions partner, or a regional reliability play—and whether the chosen position can withstand input cost pressure and procurement consolidation.
Future Outlook and Emerging Opportunities
Over the next three to five years, one of the most consequential trends will be the continued elevation of performance requirements across laboratory workflows. As experimental complexity rises and regulatory scrutiny intensifies, the demand for containers that deliver consistent thermal behavior, chemical resistance, and dimensional precision will become more widespread, not only in elite research environments but also in commercial diagnostics and manufacturing support functions. This trend creates opportunity for suppliers that can reliably document material properties, maintain tight tolerances, and support automated or semi-automated handling systems. It also raises the stakes for suppliers that depend on lower-grade substitutes in applications where failure costs are high, since buyers are more likely to absorb premium pricing when the alternative is procedural risk.
A second trend is the gradual reorientation of supply toward resilience and regional responsiveness. Procurement organizations are increasingly attentive to lead-time stability, multi-site consistency, and the risk of disruption from concentrated sourcing models. This environment favors suppliers that can offer balanced production footprints, predictable inventory availability, and clear communication around fulfillment commitments. It also opens space for regional manufacturers that can demonstrate quality reliability and quick turnaround, particularly where buyers prioritize service continuity over the lowest possible headline price. The commercial opportunity lies in building supply arrangements that reduce total operating risk, including breakage-related waste, batch rejection, and delayed testing timelines.
A third trend is the widening of product strategies from single-format glassware toward broader containment and workflow solutions. As laboratories and production environments seek to simplify procurement and standardize formats, suppliers with complementary offerings—vials, bottles, filtration-related components, precision volumetric tools, and primary packaging—can positioned themselves as workflow enablers rather than discrete item vendors. This path is especially attractive in pharmaceutical and biopharmaceutical segments, where containment decisions are closely linked to product quality and compliance narratives. The opportunity is not simply to sell more SKUs, but to reduce buyer friction by aligning container choices with downstream process needs, documentation requirements, and inventory management preferences.
PW Consulting
These trends carry inherent uncertainty. Raw material cost volatility can compress margins if not managed through mix, efficiency, or pricing discipline. Regulatory expectations may diverge across regions, complicating global standardization efforts. Competitive intensity may increase as larger players pursue acquisitions or channel expansion that narrows the Space for smaller differentiated suppliers. In addition, continued exploration of alternative materials in specific applications could limit growth in certain volume segments, particularly where weight, disposability, or cost dominates the decision calculus. Navigating these risks will require clear segmentation discipline, strong quality systems, and the ability to articulate value in terms that resonate with both technical and procurement stakeholders.
Strategic Implications for Decision-Makers
For manufacturers and suppliers, the clearest imperative is to align product portfolios with the segments where performance and compliance create durable pricing power. This means prioritizing borosilicate-based solutions in applications that demand thermal stability, chemical resistance, and auditable quality, while simultaneously pursuing efficiency improvements that offset input cost pressure. Companies should also evaluate whether portfolio expansion into adjacent containment categories or integrated solutions can reduce exposure to cyclical replacement demand and improve customer stickiness. Where regional demand is growing, investment in localized fulfillment, documentation readiness, and service responsiveness can be as important as production capacity. The strategic test is whether a supplier can move beyond being a interchangeable source of glassware to becoming a recognized contributor to workflow reliability and regulatory confidence.
For investors, the opportunity lies in distinguishing between volume-driven exposure and structurally advantaged positioning. Demand growth in the laboratory glass container market is real, but returns will be shaped by portfolio mix, cost control, channel leverage, and the ability to serve regulated or precision-oriented end-users. Businesses that combine material expertise with broader containment offerings, strong distribution relationships, and credible quality systems are better placed to convert market growth into margin expansion. Attention should also be paid to acquisition activity and channel partnerships, since these can accelerate reach and reshape competitive positioning quickly. The key question is whether a company’s strategy is built on defensible differentiation or on assumptions that commodity scale will be enough to protect profitability.
For procurement leaders and laboratory operators, the priority is to evaluate suppliers on total value rather than unit cost alone. Container performance affects reproducibility, contamination risk, breakage-related waste, and compliance documentation, all of which have downstream cost implications that can dwarf initial price differences. Standardization across sites, reliable fulfillment, and clear material specifications can reduce operational friction and improve planning predictability. Where possible, buyers should seek suppliers that can support both standardized high-volume requirements and specialized needs without forcing unnecessary compromise. In a market where concentration and channel dynamics increasingly shape availability, building resilient supplier relationships and documenting performance criteria will help protect both quality and continuity.
Conclusion
The laboratory glass container market is evolving from a mature consumables category into a performance-sensitive segment where material quality, compliance readiness, portfolio breadth, and supply reliability determine competitive outcomes. Growth through 2032 is supported by sustained scientific activity, regulatory reinforcement of higher-grade materials, and procurement behavior that increasingly values total cost and workflow integration over simple unit pricing. At the same time, the sector faces real pressures from raw material costs, market concentration, and the need to balance scale with customization. Organizations that can align their strategies with these dynamics—whether through product differentiation, channel expansion, regional responsiveness, or portfolio integration—are best positioned to capture the value available in the coming years.
For decision-makers seeking to navigate this environment with precision, deeper segmentation data, regional demand patterns, product-level growth rates, and competitive benchmarking can materially improve planning quality. PW Consulting’s comprehensive market research report provides detailed breakdowns across regions, product types, and end-user segments, along with forward-looking scenarios and customized strategic recommendations designed to support actionable decision-making. Exploring the full dataset and analysis can help translate high-level trends into specific, executable priorities.
Laboratory Glassware Market
For detailed analysis of this topic, please visit the official page: Worldwide Laboratory Glass Container Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
More Posts


Report This Post
Please complete the following requested information to flag this post and report abuse, or offensive content. Your report will be reviewed within 24 hours. We will take appropriate action as described in Findit terms of use.
