


Right Now

Navigating the Global MMP13 Antibody Market: Strategic Shifts and Commercial Opportunities Through 2032
Market Landscape and Core Challenges
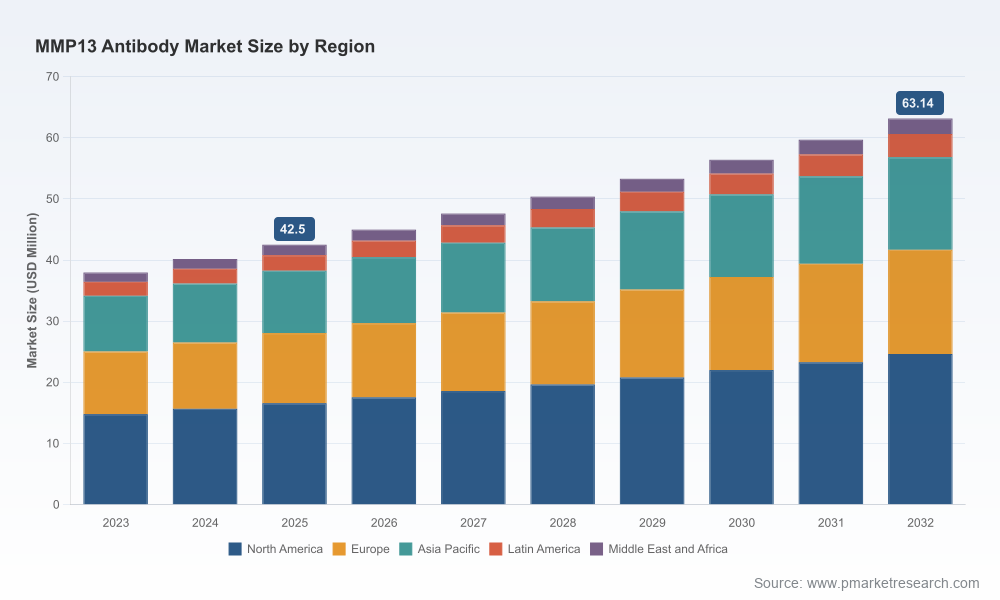
The worldwide MMP13 antibody market has established a steady upward trajectory, reaching an estimated valuation of $42.5 million in 2025. Over the historical window from 2020 through 2025, the segment expanded consistently before entering a forecast period that extends to 2032. Industry projections indicate that the market will continue to grow at a compound annual growth rate of 5.82 percent, pushing total revenue past the $63 million mark by the end of the forecast horizon. This growth path reflects a mature but still expanding research tools ecosystem, where demand is distributed across both established academic laboratories and increasingly well-funded private research organizations.
The market structure reveals a moderately concentrated landscape. The top three participants collectively account for roughly 48 percent of total revenue, while the top five firms capture approximately 62.5 percent. This concentration pattern suggests that scale, brand recognition, and validation depth still confer meaningful advantages, yet it also leaves room for specialized or agile players to capture niche demand. The presence of established multinational life science suppliers alongside focused regional or application-specific vendors creates a multi-layered competitive environment rather than a simple oligopoly.
Despite the predictable growth backdrop, the sector faces several structural challenges that will shape investment and product strategies over the coming years. Understanding these friction points is essential for decision-makers who want to align their portfolios with realistic commercial pathways rather than optimistic assumptions.
Worldwide THRAP3 Antibody Market
Validation Fragmentation and Reproducibility Pressure
One of the most persistent challenges in the MMP13 antibody space is the uneven quality and validation depth across product offerings. Researchers routinely navigate a crowded catalog where the same target is covered by dozens of clones, host species, conjugation formats, and application claims. While this variety expands choice, it also increases the burden on laboratories to verify performance in their specific experimental systems. Western blot, immunohistochemistry, ELISA, and immunocytochemistry each place different demands on antibody affinity, specificity, and epitope accessibility, meaning that a reagent performing well in one workflow may underperform in another.
The reproducibility conversation has matured beyond academic activism and now affects procurement behavior, publication standards, and reagent selection criteria. Laboratories and core facilities increasingly favor reagents with clear validation data, independent citations, and well-defined lot-to-lot consistency. Suppliers that cannot demonstrate robust application-specific evidence face longer sales cycles and higher return rates, especially in competitive procurement environments where institutional buyers compare technical documentation side by side.
Research-Use-Only Boundaries and Downstream Ambiguity
Another defining challenge is the regulatory and commercial framing of these reagents. Commercial MMP13 antibodies are designated for research use only and are not approved for diagnostic or therapeutic procedures in humans. This boundary is broadly understood, yet it still introduces ambiguity for buyers exploring translational pipelines. As more research groups study extracellular matrix remodeling, cartilage degradation, and collagenase-3 activity in disease-relevant contexts, there is growing interest in eventually moving promising targets toward clinical or diagnostic applications. Antibodies that perform reliably in laboratory settings may later need to meet far stricter characterization, stability, and compliance expectations if they are ever considered for clinical-grade development.
Oct-4 Antibody Market
This dynamic creates a strategic tension for suppliers. Products that are optimized purely for research convenience may be less attractive to organizations thinking several steps ahead, while reagents developed with future translational thinking in mind may require additional upfront investment in characterization and documentation. The market is still in a phase where the majority of demand remains firmly within laboratory workflows, but the long-term shape of the segment will partly depend on how well suppliers anticipate the documentation and reliability expectations of more applied downstream uses.
Pricing Pressure Amid Rising Experimental Complexity
Cost structures are also under pressure. Research budgets in many institutions remain constrained, while the technical expectations for antibody performance continue to rise. Buyers are increasingly comparing not just list prices but total experimental cost, including failed repeats, optimization time, and the need for supplementary reagents. At the same time, suppliers face input cost variability, quality control requirements, and the operational burden of maintaining broad catalogs with application-specific validation. The result is a market where price competition exists, but differentiation increasingly comes from reduced experimental risk rather than pure unit cost.
Key Drivers Shaping Market Direction
The market’s trajectory is not simply a function of incremental demand growth. Several interrelated forces are reshaping how MMP13 antibodies are developed, marketed, purchased, and applied. These drivers interact with one another, meaning that competitive advantage is increasingly determined by how well companies orchestrate technical, regulatory, and commercial factors rather than by any single strength in isolation.
PW Consulting
Technological Innovation and the Push Toward Recombinant and Validated Reagents
Technical evolution is one of the strongest forces behind current market growth. The broader antibody ecosystem continues to shift toward recombinant monoclonal formats, engineered clones, and reagents with stronger application-level documentation. In the MMP13 segment, this shift is visible in the expanding availability of monoclonal and recombinant options alongside traditional polyclonal antibodies. Recombinant reagents can offer advantages in consistency, immortalization of desired binding properties, and reduced reliance on animal-derived production cycles. For buyers, these attributes can translate into more predictable performance and easier scalability across projects.
At the same time, the validation conversation is becoming more application-specific. Researchers studying extracellular matrix degradation and related pathways often require reagents that work reliably in techniques such as Western blot, immunohistochemistry, ELISA, and immunocytochemistry. Providers that clearly document which applications are supported, which clones are highly cited, and which products detect particular forms of the target are better positioned to reduce buyer uncertainty. This is not only a technical issue but also a commercial one, because clear validation narratives shorten evaluation cycles and strengthen repeat purchase behavior.
Policy and Regulatory Framing Influencing Procurement and Pipeline Thinking
Regulatory context operates as a quieter but durable driver. The current framework positions MMP13 antibodies firmly in the research-use-only space, with application in laboratory techniques rather than human diagnostic or therapeutic procedures. This positioning influences procurement policies, institutional compliance reviews, and the way suppliers communicate product intent. For many buyers, the research-use designation is not a limitation but a useful boundary that defines the reagent’s role in discovery and preclinical exploration.
Still, the regulatory environment shapes more than labeling. It affects how suppliers structure quality documentation, how they anticipate future customer needs, and how they plan for any eventual movement toward more clinically adjacent workflows. Organizations that treat research-use products with rigorous characterization and transparent specifications are better prepared if customers later ask for deeper evidence packages or if translational interest increases. In this sense, regulatory framing pushes the market toward higher documentation standards even before any formal diagnostic or therapeutic pathway is in view.
Demand-Side Shifts Toward Targeted Extracellular Matrix and Disease-Relevant Research
Demand behavior is evolving as research priorities become more targeted. MMP13 remains closely associated with collagenase-3 activity and extracellular matrix remodeling, which keeps it relevant across multiple research themes. Rather than treating the antibody as a generic research tool, many groups now evaluate it in the context of specific biological questions, such as cartilage degradation, wound healing processes, and tumor-related matrix remodeling. This shift encourages buyers to choose reagents based on fit for particular experimental models rather than on broad catalog availability alone.
This demand-side change matters commercially because it increases the value of application alignment. Suppliers offering reagents explicitly positioned for osteoarthritis research, oncology research, tissue remodeling, and wound healing contexts can capture more focused purchasing decisions. It also encourages repeat usage when a reagent becomes embedded in a lab’s standard workflows for a specific research program. Over time, this dynamic favors companies that can communicate both technical performance and biological relevance without overstating the reagent’s role.
Supply Chain and Cost Dynamics Encouraging Portfolio Discipline
Supply-side considerations are becoming more strategic. Maintaining a broad antibody catalog is operationally intensive, particularly when suppliers aim to support multiple applications, host species, and validation claims. At the same time, buyers are more willing to consolidate around trusted vendors if they believe they can reduce variability and sourcing complexity. This creates a pull toward portfolio discipline, where companies must decide which products to expand, which to sunset, and which to support with stronger technical documentation.
Cost structures are also being reevaluated through the lens of total experimental value. A lower-priced antibody that requires extensive optimization may carry higher hidden costs than a better-characterized alternative. Suppliers that can reduce downstream friction for customers gain leverage even in price-sensitive environments. This is especially relevant in a market where demand is spread across many smaller laboratories and research units, each with limited tolerance for reagent failure.
Competitive Landscape and Leading Strategies
The MMP13 antibody market features a diverse competitive field that blends large multinational suppliers with more specialized providers. The leading companies do not compete solely on price; they compete on catalog breadth, validation depth, application fit, brand trust, and the ability to support repeat research workflows. Understanding how these players position themselves provides a useful map for organizations deciding where to enter, expand, or defend.
Incumbent Scale and Catalog Breadth as a Defensible Base
Large, established life science companies benefit from broad distribution networks, strong brand recognition, and the ability to cross-sell across related product lines. In the MMP13 space, some of the most visible players maintain extensive catalogs with multiple antibody formats, including both polyclonal and monoclonal options. This breadth allows them to serve a wide range of laboratory needs and to capture demand from buyers who prefer to source multiple reagents from a single trusted vendor.
For these incumbents, the strategic advantage is not just size but the credibility that comes from scale and continuity. A broad offering can reduce the likelihood that a customer leaves for a niche supplier over a single product need. At the same time, large catalogs must be managed carefully; if too many products lack clear differentiation or strong validation narratives, the catalog can become harder to navigate and harder to trust. The winners in this tier typically combine catalog scale with selective emphasis on the best-supported clones and applications.
Specialization and Application-Focused Positioning
Smaller or more focused suppliers often compete by building depth around specific applications, host species, or research contexts. Some providers have gained visibility through highly cited reagents or products explicitly aligned with workflows such as Western blot, immunohistochemistry, ELISA, or immunocytochemistry. In a market where experimental fit matters greatly, this type of positioning can be powerful. A reagent that is well recognized in a particular application can become a default choice for laboratories pursuing that workflow.
This specialization also allows companies to invest more intensely in documentation and customer support for a narrower set of products. Instead of trying to be everything to everyone, they can create stronger technical stories around specific clones or detection formats. The risk, of course, is that a highly narrow focus can limit upside if demand patterns shift. The most resilient specialists tend to balance narrow strength with enough flexibility to adapt as research priorities evolve.
Portfolio Clustering and the Value of Trusted Brand Ecosystems
A notable feature of the competitive landscape is the way brands and portfolios are clustered. Some organizations are associated with well-known reagent families or distributed through established commercial platforms. This clustering matters because researchers often evaluate products within an ecosystem they already trust. If a supplier’s broader brand is associated with reliable performance, clear documentation, and responsive support, individual antibody products inherit part of that trust.
This dynamic encourages a strategy of ecosystem reinforcement. Companies that can connect MMP13 antibodies to related tools, consistent quality standards, and coherent application guidance often gain an advantage in purchase decisions. The competitive edge is less about any single product attribute and more about the cumulative confidence a buyer feels when choosing a vendor for repeated experimental work.
Market Evolution Toward Consolidation, Differentiation, and Selective Entry
Looking at the overall structure, the market appears likely to keep moving in two directions at once. On one hand, concentration among the strongest performers may increase as laboratories consolidate purchasing around vendors with the strongest validation packages and service reliability. On the other hand, differentiation will remain important because application needs are not uniform, and there will continue to be room for reagents that solve specific workflow problems.
New entrants face a realistic challenge: the market is not empty, and trust is hard-won. Successful entry usually depends on offering a clear technical advantage, a strong validation story, or a better fit with an underserved application context. Pure commodity entry is difficult because buyers already have many options. Entry based on reproducible performance, convenient format, or clearly documented application support is far more viable. Over time, the market is likely to see selective consolidation among weaker catalog players and continued pressure on suppliers who cannot differentiate beyond list price.
Future Trends and Commercial Implications
Projecting the next three to five years requires balancing steady demand growth with the market’s structural pressures. Several trends are likely to shape how the MMP13 antibody segment develops, and each carries distinct commercial implications.
More Rigorous Validation as a Market Standard, Not a Differentiator
Validation expectations will likely keep rising. What is today considered a competitive advantage may become baseline expectation within a few years. Laboratories, core facilities, and institutional procurement teams are increasingly accustomed to comparing documentation quality, citing performance in specific applications, and avoiding reagents with ambiguous evidence. As this expectation spreads, suppliers will need to invest more in application-specific data, lot consistency, and transparent product narratives.
The commercial implication is that validation will become a cost of staying in the market as much as a source of advantage. Companies that treat documentation as an afterthought may find themselves pushed toward lower-margin, more price-sensitive segments. Those that build credible validation packages early are more likely to retain premium positioning and reduce customer churn.
Continued Blending of Polyclonal and Monoclonal Strategies
The market is likely to continue supporting both polyclonal and monoclonal antibodies, but with different strategic roles. Polyclonal reagents may remain valuable where broad epitope recognition or particular experimental histories matter, while monoclonal and recombinant formats may increasingly serve buyers prioritizing consistency and scalability. The exact mix will vary by application and customer type, but the overall trend points toward a more deliberate matching of format to use case.
For commercial strategy, this suggests that the most effective portfolios will not simply maximize product count. They will align formats with demand patterns, clearly explain when one format is preferable to another, and reduce the confusion that can arise when similar products are listed without enough context. In practice, that means stronger product storytelling and more precise application guidance.
Growing Emphasis on Workflow Reliability and Total Cost of Ownership
As laboratories optimize limited budgets and time, they are likely to weigh reagents more heavily on total workflow impact. A product that saves optimization time, reduces repeat experiments, or integrates smoothly into established assays may win preference even if the upfront price is not the lowest. This trend favors suppliers who can demonstrate practical reliability and who support customers with clear protocols, responsive technical engagement, and consistent product performance.
The commercial opportunity here lies in shifting the conversation from price-per-tube to cost-per-answer. Organizations that can articulate how their reagents reduce experimental risk may be able to defend stronger pricing and build deeper customer relationships. The risk is that suppliers who compete only on listing price may face margin erosion without gaining durable loyalty.
Potential Risks and Uncertainties
Despite the generally constructive outlook, several uncertainties bear watching. Regulatory framing may continue to limit how research-use products are positioned, which is fine for the current market but could complicate any future translational ambitions. Demand can also shift if research funding patterns change or if competing experimental approaches reduce dependence on certain antibody-based workflows. In addition, reproducibility expectations and procurement consolidation could raise the barrier for smaller players who lack strong documentation or brand trust.
There is also the unavoidable risk that market growth, while positive, does not solve the underlying challenge of product differentiation. If too many suppliers offer similar claims without clear evidence, customers may become more conservative in adoption and more sensitive to failure. The companies most likely to navigate these uncertainties well are those that treat transparency, validation, and application fit as long-term strategic assets rather than short-term marketing elements.
Strategic Actions for Decision-Makers
The MMP13 antibody market rewards players who think in terms of evidence, fit, and customer workflow rather than catalog size alone. The following actions are most relevant depending on an organization’s role in the value chain.
For Manufacturers and Suppliers
- Prioritize application-specific validation and make it easy for buyers to see which workflows a product genuinely supports.
- Rationalize catalogs so that each product has a clear reason to exist, whether that is clone specificity, format advantage, or citation strength.
- Invest in documentation and technical communication that reduce buyer evaluation time, since faster trust-building often matters more than marginal price differences.
- Consider how current research-use positioning can be supported by rigorous quality practices that keep options open for future translational or applied interest.
For Investors
- Evaluate opportunities based on validation depth, repeat-purchase potential, and the ability to serve focused workflows rather than relying on broad market growth narratives alone.
- Look for companies that combine credible technical differentiation with operational discipline, because scale without differentiation is vulnerable to price competition.
- Monitor consolidation trends carefully; there may be value in platforms that can integrate complementary products, strengthen documentation standards, and improve procurement convenience for buyers.
- Assess downside risk from reproducibility pressure and buyer consolidation, especially for suppliers with undifferentiated catalogs or weak application support.
For Procurement and Research Buying Teams
- Evaluate reagents on total experimental value, including validation clarity, application fit, and the likelihood of consistent performance across projects.
- Standardize evaluation criteria across groups to reduce reliance on anecdotal recommendations and to make it easier to compare products with similar listings.
- Favor suppliers that provide clear documentation and stable support, since these attributes often reduce hidden costs in optimization and repetition.
- Track product performance internally and share feedback where possible, because institutional experience can strengthen future purchasing decisions and improve workflow efficiency.
Strategic choices in this market are most effective when they are based on current, granular data rather than on broad impressions of growth. Segment-level demand patterns, application mix, regional procurement behavior, and company-level positioning all influence where value is created and where risk accumulates. Readers seeking a fuller picture with more detailed breakdowns and tailored strategic implications can access the complete PW Consulting market analysis for deeper commercial context.
For detailed analysis of this topic, please visit the official page: Worldwide MMP13 Antibody Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
More Posts


Report This Post
Please complete the following requested information to flag this post and report abuse, or offensive content. Your report will be reviewed within 24 hours. We will take appropriate action as described in Findit terms of use.
