


Right Now

Navigating the N-Allylamine Market: Strategic Trends and Commercial Opportunities Through 2032
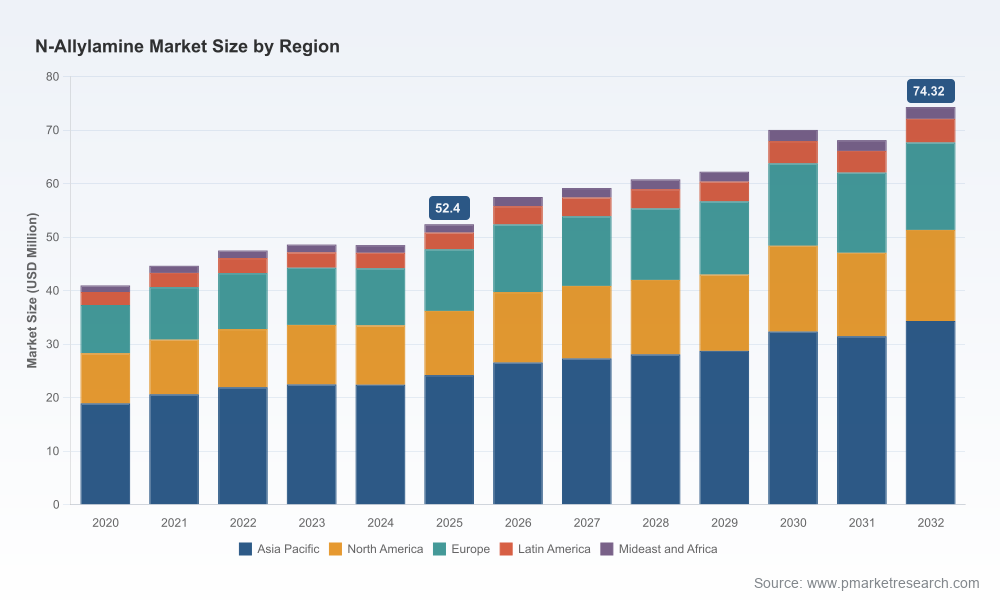
The global N-Allylamine market has entered a phase of measured growth, underpinned by steady expansion in specialty chemicals and a structural shift toward higher-purity grades. Valued at approximately 52.4 million in 2025, the market has rebounded from a brief plateau around 2023–2024 and is projected to reach 74.32 million by 2032, translating to a compound annual growth rate of 5.12 percent across the 2026–2032 forecast window. This trajectory is not merely a function of volume expansion; it reflects a maturing supply base, tightening specification requirements from downstream users, and regional reallocations of production capacity. For executives and investors, the opportunity lies less in chasing raw tonnage and more in aligning with the segments where purity, reliability, and technical support command premium positioning.
Beneath the headline figures, the industry is navigating a set of inflection points that will determine which players capture margin and which get squeezed into commoditization. The following sections examine the forces reshaping demand and supply, the competitive strategies that are differentiating incumbents from challengers, and the near-term trends that will shape capital allocation and procurement decisions over the next three to five years.
Market Snapshot and Core Challenges
The market's recent trajectory illustrates a recovery pattern rather than linear growth. After a period of consolidation around 48–49 million during 2023–2024, revenue moved back above 52 million in 2025 and is expected to approach 60 million by 2027 before scaling toward 70 million in the latter half of the decade. This pattern signals a market that is sensitive to demand cycles in pharmaceuticals, water treatment, and polymer synthesis, while also responding to capacity additions and regional cost dynamics. Growth is broad-based but uneven, with certain application verticals and purity segments expanding faster than the aggregate.
Three structural challenges warrant attention as the market scales:
- Purity as a bar, not a differentiator – Higher-purity grades are becoming the default expectation in pharmaceutical intermediates and fine chemical synthesis, narrowing the window for low-cost, lower-specification offerings. Suppliers that cannot consistently deliver tight specifications face eroding relevance in value-critical applications.
- Regional cost and supply realignment – Production footprints are shifting in response to energy costs, environmental compliance, and logistics considerations. The result is a more fragmented cost landscape where competitive advantage depends on localized sourcing strategies and resilient logistics rather than on a single global price benchmark.
- Qualification cycles and customer switching costs – In pharma and agrochemical workflows, N-Allylamine is frequently embedded into multi-step processes with rigorous qualification requirements. This creates stickiness for incumbent suppliers but also lengthens the path for new entrants seeking traction in regulated segments.
For decision-makers, these challenges reframe the strategic question. The market is not simply getting bigger; it is getting more specification-driven and regionally contingent. The commercial winners will be those who align capacity and service models with where approvals, purity thresholds, and delivery reliability matter most.
Allyl Alcohol Market
Key Drivers Reshaping the Market
Technical Innovation and Process Refinement
Progress in synthesis and purification is quietly raising the floor for what suppliers can deliver at scale. Continuous and semi-continuous processing, improved distillation and separation steps, and tighter control over reaction conditions are helping manufacturers reduce batch-to-batch variability and lower impurity profiles. In practical terms, this means more consistent high-purity output at lower operational risk — a critical consideration for pharmaceutical intermediates and polymer synthesis, where trace contaminants can cascade into downstream quality issues. Innovation here is less about dramatic breakthroughs and more about incremental process reliability that compounds into a defensible service advantage.
PW Consulting
Regulatory and Compliance Pressures
Regulatory scrutiny is increasingly shaping both supply and demand. Environmental and occupational health requirements are influencing plant design, emission controls, and handling protocols, which in turn affect capital intensity and time-to-market for capacity expansions. On the demand side, pharmaceutical and agrochemical customers are tightening supplier qualification standards, placing a premium on documentation, traceability, and consistent conformance. These dynamics favor suppliers that have already embedded compliance into their operating model, while raising the entry threshold for less-established players.
Demand-Side Evolution in Key Verticals
End-use demand is being reshaped by application-specific growth vectors. In pharmaceutical intermediates, the push toward more complex synthesis routes and higher-quality inputs continues to support demand for higher-purity material. Water treatment chemicals represent another steady demand pool, driven by municipal and industrial water management needs. Polymer synthesis and epoxy resin-related formulations add a more cyclical but structurally meaningful layer of demand, particularly where formulations require reliable reactive amine functionality. The net effect is a demand base that is diversified enough to cushion sector-specific softness but concentrated enough that purity and application expertise still matter.
Supply Chain and Cost Structure Dynamics
Cost competitiveness is increasingly determined by how well suppliers manage feedstocks, energy exposure, and logistics across regions. Regional cost disparities, shifting trade flows, and the need to buffer against volatility are encouraging more localized sourcing strategies and dual-supplier arrangements. At the same time, customers are balancing price with assurance — favoring suppliers that can reduce qualification risk and delivery uncertainty even when unit pricing is not the lowest on the market. In this environment, cost leadership is no longer purely about input price; it is about total cost of ownership across qualification, reliability, and compliance.
Competitive Landscape and Leading Strategies
The supplier base is defined by a mix of specialty chemical manufacturers, research-grade and laboratory-scale distributors, and fine chemical producers with export-oriented operations. Incumbents differentiate not just on volume but on specification control, application support, and the ability to serve both small-scale research and larger industrial requirements. Several strategic postures are visible across the landscape:
- High-purity, application-focused positioning – Companies that emphasize high-purity grades for organic synthesis and pharmaceutical intermediates position themselves as enablers of downstream quality rather than commodity suppliers. This orientation tends to align with more stable demand from regulated and quality-sensitive users.
- Dual-scale capability – Some suppliers operate across lab-scale and bulk quantities, allowing them to support early-stage development while remaining relevant as projects move toward production. This continuity can deepen customer relationships and improve visibility into future demand.
- Export-oriented fine chemical manufacturing – Producers with established export channels are building relevance in pharmaceutical, agrochemical, and epoxy resin markets by combining manufacturing scale with international distribution. Their advantage lies in reaching multiple end markets without relying on a single regional demand cycle.
- Comprehensive catalog reach and technical reputation – Broader chemical portfolios and recognized brand presence in research and industrial channels help suppliers capture share in laboratory and small industrial use cases, where procurement decisions often weigh accessibility, documentation, and technical trust alongside price.
The market structure reflects moderate concentration at the top, leaving meaningful room for specialized players and regional suppliers to compete on service, specification, and responsiveness. Over time, two opposite forces are likely to shape the landscape: consolidation among larger integrated suppliers seeking broader geographic and application coverage, and continued fragmentation in niche, high-purity, or regionally focused segments where agility and technical relationships matter more than scale alone. New entrants will find the most traction where they can solve a specific qualification, purity, or delivery pain point rather than compete head-on on general-purpose volume.
Forward Outlook: Three to Five Year Trends
Looking ahead, several trends are likely to define the commercial environment and open distinct opportunities:
- Purity thresholds move higher across more applications – As downstream processes become more demanding, the share of higher-purity material in the mix is expected to keep rising. The commercial implication is a margin mix that tilts toward specification-sensitive segments, rewarding suppliers with robust quality systems and documented consistency.
- Regionalization of supply and procurement – Buyers are likely to diversify sources and increase regional sourcing to reduce exposure to logistics shocks and regulatory shifts. Suppliers with localized capacity, flexible logistics, and clear compliance credentials will be better positioned to win multi-source agreements and retain share during disruptions.
- Application-led growth in pharma intermediates and water treatment – These areas are expected to remain durable demand anchors, with pharma driving purity-led value and water treatment providing steadier volume underpinnings. Opportunities will accrue to suppliers that can map their offerings to specific formulation and process needs rather than selling a generic intermediate.
These trends carry uncertainty. Demand in polymer and epoxy-linked applications may fluctuate with construction and industrial cycles. Regulatory changes can alter cost structures and approval timelines. Trade and logistics dynamics can shift regional competitiveness quickly. The market is therefore best approached as a portfolio of subsegments with different sensitivities, rather than as a single homogeneous growth story.
Strategic Recommendations for Decision-Makers
For manufacturers, the priority is to align production and quality systems with the specification levels that command premium positioning. Investments that reduce variability, strengthen documentation, and improve responsiveness to customer qualification needs will tend to pay off more than undifferentiated volume expansion. Where possible, building flexible capacity that can serve both research-scale and industrial-scale demand can improve visibility into downstream adoption and smooth cyclicality.
For investors, the most informative lens is subsegment differentiation rather than aggregate size. Opportunities are likely to be concentrated where purity, compliance, and reliability translate into structural pricing power, and where regional supply realignment creates openings for credible new or expanded capacity. Due diligence should probe not only current revenue composition but also the pipeline of qualified applications, the stability of key customer relationships, and the cost position under varying energy and logistics scenarios.
Worldwide Allyl Methacrylate Market
For procurement and sourcing leaders, the tactical imperative is to manage total cost of ownership rather than unit price in isolation. Dual-sourcing strategies, clear specification alignment, and supplier qualification readiness can reduce the risk of process interruptions and speed onboarding when demand shifts. Engaging suppliers early on documentation, lot consistency, and delivery flexibility often proves more valuable than negotiating small price differences on a commodity input.
Depth matters in a market where segment-level purity mix, regional cost positions, and application qualification cycles can change the economics quickly. A detailed research report can help translate the macro direction into segment-level sizing, regional contrasts, and company-specific positioning that inform capital allocation, sourcing strategy, and market entry decisions. For teams that need to move from directional confidence to executable planning, a full study with granular segmentation and customized scenarios is the natural next step.
For detailed analysis of this topic, please visit the official page: Worldwide N-Allylamine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
More Posts


Report This Post
Please complete the following requested information to flag this post and report abuse, or offensive content. Your report will be reviewed within 24 hours. We will take appropriate action as described in Findit terms of use.
