


Right Now

Strategic Shifts in the Global Urethritis Drugs Market: Opportunities Amid Rising Resistance and Innovation
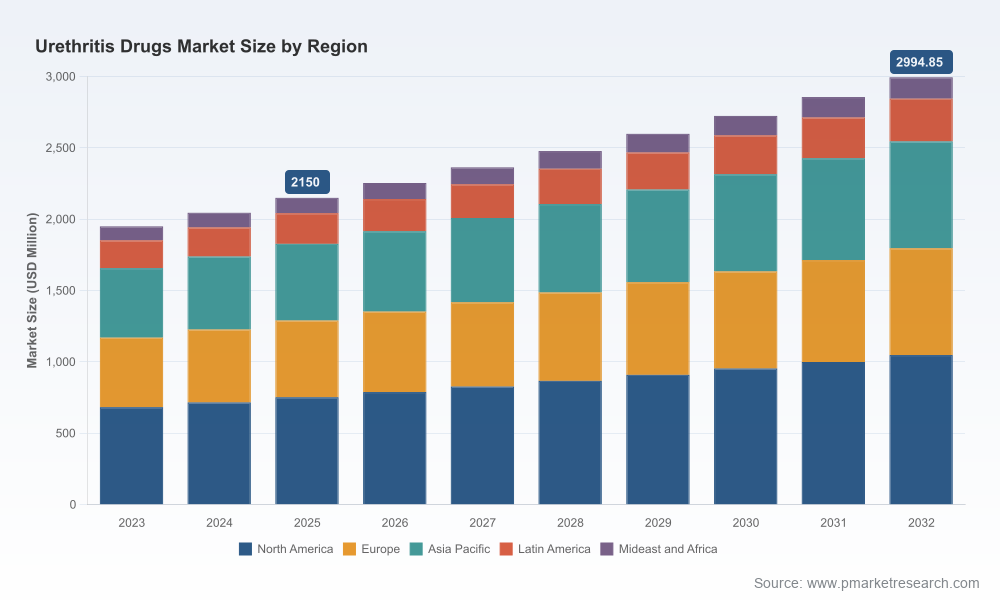
The global urethritis drugs market has entered a phase of measured expansion, characterized by steady revenue growth and evolving therapeutic standards. In 2023, the market generated approximately USD 1,950 million in revenue, which edged up to USD 2,045.5 million in 2024 and reached USD 2,150 million in 2025. This trajectory reflects a compound annual growth rate of roughly 4.85% through 2032, positioning the sector as a stable yet strategically dynamic segment within the broader infectious disease and urology therapeutics landscape. By 2032, projected market revenues are expected to approach USD 2,994.85 million, underscoring a long-term expansion arc driven by sustained demand for effective bacterial infection management, expanded access to care, and incremental product development.
Within this growth footprint, geographic and distribution dynamics reveal a market that is simultaneously mature in established healthcare systems and increasingly accessible in emerging regions. North America has historically captured the largest share of revenue, reflecting high diagnostic penetration, established reimbursement pathways, and strong uptake of guideline-recommended regimens. Europe and Asia Pacific represent substantial and broadly comparable revenue bases, each shaped by distinct healthcare financing models, population health priorities, and antibiotic utilization patterns. Latin America and the Middle East and Africa contribute smaller but strategically important portions of the market, where public health programs and expanding primary care access are gradually reshaping treatment utilization. In terms of therapy categories, both gonococcal urethritis and non-gonococcal urethritis drug segments hold meaningful revenue weight, with non-gonococcal therapies representing the larger portion of the market. Distribution channels remain diversified, with retail pharmacies accounting for the largest share of dispensing activity, hospital pharmacies forming a significant second channel, and online pharmacies representing a smaller but rapidly growing route to patient access.
The competitive arena is moderately consolidated but not rigidly so. The top three players collectively hold roughly 28.5% of market revenue, while the top five account for approximately 39.2%. This concentration indicates room for both incumbents and challengers to gain share through product differentiation, supply reliability, formulation innovation, and regional execution. Against this backdrop, the market is less defined by scale alone and more by the ability to adapt to shifting clinical standards, antimicrobial resistance pressures, and changing access pathways.
PW Consulting
Market Fragility and the Turning Points Shaping Competitive Strategy
Even within a stable growth outlook, the market faces structural vulnerabilities that are reshaping decision-making for manufacturers, buyers, and investors. Three challenges stand out as particularly consequential for forward-looking strategy.
First, antimicrobial resistance is reconfiguring treatment assumptions across both gonococcal and non-gonococcal urethritis. Rising resistance patterns in organisms associated with non-gonococcal urethritis, including Mycoplasma genitalium and certain Haemophilus species, are eroding the reliability of standard empiric regimens. This resistance dynamic is not merely a clinical concern; it is a commercial one. When first-line therapies lose effectiveness, treatment cycles lengthen, repeat visits increase, and demand can shift toward newer or more targeted agents. At the same time, resistance also pressures generic pricing and formulary positioning when public health programs seek to preserve the utility of existing antibiotics through stewardship measures.
Second, regulatory and clinical guideline updates are creating a moving target for product positioning and procurement planning. Major guideline bodies continue to refine treatment recommendations for both gonococcal and non-gonococcal urethritis, emphasizing dual-therapy considerations, resistance-aware prescribing, and regimen preferences that favor certain antibiotic classes in specific scenarios. For manufacturers, this means that clinical endorsement can influence demand trajectories quickly, while for buyers, it introduces the need to monitor guideline revisions as part of formulary and inventory strategy. The commercial implication is clear: in a market where standard-of-care can change in response to resistance data or public health recommendations, agility matters as much as product strength.
Third, cost dynamics in antibiotic manufacturing and supply chains are reshaping competitive advantage at a time when price sensitivity remains high. Broad access to affordable generic antibiotics has supported treatment scale, but reliance on established global supply chains also creates exposure to raw material variability, API sourcing concentration, and regional production constraints. As a result, supply reliability, cost control, and the ability to secure consistent availability are becoming differentiators, particularly for buyers managing public health programs and for manufacturers seeking to defend or expand market position in cost-competitive segments.
What Is Actually Driving the Market Forward
The market’s growth is not simply a function of disease prevalence. It is being shaped by a combination of clinical innovation, regulatory direction, demand-side behavior, and supply chain economics. Understanding these drivers is essential for anyone evaluating where value will be created over the next several years.
A primary driver is the emergence of new antibiotic options that address limitations in current treatment paradigms. The commercial significance of pipeline progress was underscored in 2025 when GlaxoSmithKline received FDA approval for Blujepa, a novel antibiotic indicated for uncomplicated gonorrhea, including male urethritis caused by Neisseria gonorrhoeae. This approval illustrates a broader theme: therapies that offer differentiated mechanisms or simplified dosing can capture attention in a market where resistance and treatment adherence are persistent concerns. Alongside this, the release of Phase 3 trial results for zoliflodacin, a single-dose oral treatment evaluated against the ceftriaxone-plus-azithromycin regimen for uncomplicated urogenital gonorrhea, reinforced growing interest in oral, single-dose approaches that could improve adherence and reduce treatment burden. These developments matter commercially because they expand the field of plausible future standards of care and create new positioning opportunities for companies able to bring differentiated products to market at scale.
Policy and regulatory environments are another powerful driver. Public health guidance continues to influence prescribing habits, formulary inclusion, and program-based purchasing. CDC STI treatment recommendations have historically shaped preferred regimens for nongonococcal urethritis, while WHO recommendations have increasingly accounted for antimicrobial resistance in gonococcal treatment decisions. For the market, this means that guideline alignment can accelerate adoption of specific drugs while also reinforcing the importance of stewardship. It also means that manufacturers and suppliers need to treat regulatory and clinical guidance as a strategic input, not just a compliance matter. When guidance shifts, demand patterns can follow, and the companies best prepared to respond with supply flexibility, clinical support, and formulation readiness tend to capture more durable positioning.
On the demand side, the market is being influenced by changing patient access patterns and evolving expectations around convenience. Retail pharmacies remain the dominant dispensing channel, reflecting their broad reach and established role in community-based care. At the same time, the presence of hospital pharmacies as a major channel underscores the continued importance of clinically supervised treatment pathways, especially for cases requiring coordinated diagnosis and follow-up. Online pharmacy channels, while smaller today, represent a growing wedge in the market as digital access to medications expands in certain regions. For manufacturers and distributors, this channel mix is strategically relevant because it affects how products reach patients, how pricing and reimbursement are managed, and how brand or generic positioning translates into real-world uptake. In practice, the growing role of alternative channels suggests that future competition will increasingly involve not just clinical efficacy but also distribution access, patient convenience, and digital purchasing pathways.
Finally, supply-side economics are reinforcing the importance of cost control and manufacturing resilience. Generic competition in antibiotics such as azithromycin and doxycycline has helped keep treatment costs manageable and supported broad access across multiple markets. Yet this same competitive intensity also compresses margins and raises the stakes for operational efficiency. Companies that can balance cost-effective production with reliable availability are better positioned to serve both public-sector buyers and retail distribution networks. More broadly, the reliance on established API supply chains means that market participants need to consider sourcing strategy, manufacturing continuity, and regional capacity as competitive levers, especially as demand becomes more sensitive to both affordability and supply assurance.
Competitive Positioning: Who Is Playing How, and Where the Field Is Moving
The leaders in this market are pursuing broadly different strategies, and those differences reveal where competitive advantage is being built. Pfizer remains a recognizable force through its established azithromycin and ceftriaxone-related offerings, which align with widely used treatment regimens for gonococcal and nongonococcal urethritis. Its strategic positioning is rooted in a recognized brand portfolio, clinical familiarity, and distribution reach. In a market where guideline-recommended therapies still anchor much of demand, incumbents with strong associations to standard regimens can benefit from continued formulary inclusion and clinician trust.
GSK illustrates a more innovation-oriented posture. With the FDA approval of Blujepa for gonococcal infections including urethritis, GSK is expanding its relevance in STI treatment through a differentiated antibiotic approach. Its broader antibiotic and anti-infective portfolio provides additional context for its strategy: the company is seeking to combine new product momentum with an established therapeutic footprint. For competitors, the key takeaway is that investment in novel mechanisms and regulatory execution can open space in a market where generic dominance otherwise makes differentiation difficult.
Worldwide Conjunctivitis Ophthalmic Drugs Market
The Indian generic manufacturers, including Teva, Sun Pharma, Cipla, and Dr. Reddy’s, represent a crucial competitive layer. These companies compete largely through affordability, scale, and broad supply of azithromycin, doxycycline, and related antibiotics used in first-line treatment protocols. Their strategic advantage lies in cost efficiency, global sourcing capability, and the ability to serve diverse markets, from high-volume retail distribution to public health programs. In many regions, this generic base is what sustains access and keeps treatment costs within reach. The commercial implication is that generic manufacturers are not merely price players; they are access enablers, and their ability to maintain reliable supply, quality standards, and cost discipline directly affects market stability.
AbbVie and Merck round out the landscape with antibiotic and anti-infective exposure relevant to broader bacterial infection management. Their positioning reflects the reality that urethritis treatment does not exist in isolation. Companies with broader infectious disease portfolios can leverage cross-product capabilities, clinical expertise, and commercial infrastructure, even if urethritis-specific revenue is only one part of a larger picture. This suggests that competitive dynamics in the market may increasingly involve firms that view urethritis therapies through the lens of a wider anti-infective strategy.
The competitive landscape is evolving along several axes. In one direction, there is potential for consolidation among generic and specialty players seeking to strengthen supply networks, expand geographic reach, or consolidate manufacturing capacity. In another, the market is also open to differentiation by new entrants with novel antibiotics or improved delivery profiles, particularly if resistance continues to undermine the durability of existing regimens. The balance between consolidation and new entry will depend on how quickly resistance-driven demand shifts translate into commercial opportunity, and how effectively regulators and buyers support access to newer agents without destabilizing affordable treatment options.
Where the Market Is Likely Headed Over the Next 3 to 5 Years
Looking ahead, three trends are likely to define the market’s direction and shape where commercial opportunity emerges.
The first trend is a gradual shift toward resistance-aware treatment strategies and more targeted therapy selection. As resistance patterns continue to influence clinical decision-making, there will be increasing value in products, diagnostics, and service models that support resistance-guided prescribing. This could benefit companies offering differentiated antibiotics, but it also creates room for broader commercial approaches that combine therapy with diagnostic support, stewardship information, or clinician education. For businesses, the opportunity lies in aligning product strategy with the practical reality that clinicians and programs will increasingly need to manage uncertainty in pathogen response, not just dispense standard regimens.
The second trend is the expanding role of convenience-oriented treatment models. Single-dose oral options, simplified regimens, and channel flexibility will continue to gain relevance because they address adherence, follow-up burden, and patient experience. The Phase 3 zoliflodacin data and the approval of Blujepa both point in this direction, even if commercial adoption will depend on pricing, access, and local guideline integration. For manufacturers and distributors, this suggests that future success may rely as much on delivering convenient, reliable treatment pathways as on the clinical attributes of the molecule itself. Channel strategy will matter here too, especially as patients and providers increasingly expect smoother access across retail, hospital, and digital channels.
The third trend is growing pressure on affordability and supply continuity. Even as innovation introduces new therapies, the bulk of market volume will remain tied to cost-sensitive segments where generic access is essential. Over the next several years, buyers will likely continue to weigh clinical updates against budget realities, and suppliers will need to demonstrate that they can provide consistent availability at competitive cost. Companies that overinvest in premium positioning without maintaining access economics may find limited traction in high-volume parts of the market, while those that can combine reliable supply with reasonable cost structures will remain strategically important.
These trends do not point in a single direction. They create a market in which innovation and access must be balanced, and in which commercial success will depend on managing both clinical credibility and operational practicality. The risk side is equally important: resistance could shift demand faster than expected, guideline changes could alter preferred regimens in ways that disrupt legacy product positioning, and supply or pricing pressures could compress margins in generic-heavy segments. In addition, the introduction of new therapies may face hurdles related to reimbursement, adoption speed, and competition from entrenched low-cost alternatives.
Strategic Implications for Different Decision-Makers
For manufacturers, the strategic priority is to build portfolios that can respond to both resistance evolution and access economics. That means maintaining strong execution in high-volume generic segments while also pursuing differentiated opportunities where novel mechanisms, improved dosing, or targeted indications can create defensible value. Equally important is supply chain resilience. In a market where availability and cost directly influence purchasing decisions, manufacturing reliability and API sourcing strategy can be as influential as product features. Companies should also treat clinical guideline developments as a core input to planning, since changes in preferred regimens can shift demand among established therapies and create openings for newer options.
Bacterial Vaginosis Drug Market
For investors, the market rewards a careful balance between stability and disruption. The broad revenue trajectory is positive, and demand is underpinned by ongoing need for effective urethritis treatment, but the most meaningful upside may come from companies with credible innovation pipelines, strong regulatory execution, and the ability to navigate resistance-driven changes in standard of care. At the same time, investors should monitor concentration dynamics, generic pricing pressure, and the commercial traction of newer agents. The presence of both established incumbents and active pipeline development means that value creation may be uneven, with some players gaining from differentiation while others defend position through scale and cost leadership.
For procurement organizations and healthcare buyers, the immediate priority is to manage guideline alignment, formulary readiness, and supply assurance in tandem. Because treatment recommendations can evolve in response to resistance data and public health guidance, procurement strategies should be built with enough flexibility to accommodate regimen changes without disrupting access. This includes evaluating supplier reliability, monitoring availability across hospital and retail channels, and ensuring that preferred products remain aligned with current clinical guidance. In markets where public health programs play a significant role, affordability and continuity will remain central, so buyers should balance the appeal of newer options with the practical need to secure consistent, cost-effective supply for the bulk of patient demand.
Across all of these perspectives, one theme is consistent: the urethritis drugs market is no longer a static segment defined solely by established antibiotics and routine prescribing. It is a market being reshaped by resistance realities, new therapeutic entrants, guideline evolution, and changing access channels. Those forces create both risk and opportunity, and they reward organizations that can interpret the shifting landscape early rather than simply react to it.
Detailed segmentation data, company-level revenue context, regional growth differentials, procurement dynamics, and forward scenarios can help translate this high-level picture into specific planning assumptions. For decision-makers who need a more granular view of pricing pressure, distribution shifts, competitive moves, and therapeutic adoption pathways, the full market research report provides a deeper foundation for strategy development and investment evaluation.
For detailed analysis of this topic, please visit the official page: Worldwide Urethritis Drugs Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
More Posts


Report This Post
Please complete the following requested information to flag this post and report abuse, or offensive content. Your report will be reviewed within 24 hours. We will take appropriate action as described in Findit terms of use.
