


Right Now

Strategic Trends and Commercial Opportunities in the Worldwide 2-Cyanobenzyl Bromide Market
The global market for 2-cyanobenzyl bromide has entered a phase of steady, structurally supported expansion. Valued at approximately USD 38.45 million in 2020, the market reached USD 50.8 million by 2025, reflecting a compound annual growth rate of 5.82 percent over the 2020–2025 period. Projections indicate the market will continue its upward trajectory, moving from USD 52.73 million in 2026 to USD 75.4 million by 2032, sustained by consistent demand from pharmaceutical synthesis, agrochemical development, and specialized research applications. This growth profile is not merely a function of volume expansion; it reflects deeper shifts in how fine chemical intermediates are sourced, purified, and integrated into downstream manufacturing workflows. Understanding the strategic inflection points within this market requires looking beyond headline figures and examining the operational, regulatory, and competitive forces shaping supply and demand dynamics.
For executives and strategic planners, the market presents a paradox: it is growing predictably, yet it remains fragmented, price-sensitive, and subject to regulatory and feedstock volatility. The compound serves as a critical building block in multi-step synthesis pathways, particularly in the production of pharmaceutical active pharmaceutical ingredients and specialized agrochemical formulations. Its role as an intermediate means that demand is indirectly tied to the success and scale-up timelines of downstream drug candidates, crop protection molecules, and custom research projects. This indirect linkage creates both opportunities and vulnerabilities. Manufacturers and buyers alike must navigate purity requirements, batch consistency, compliance documentation, and shifting cost structures, all while competing in a landscape where geographic concentration, product grade differentiation, and application-specific value chains dictate market positioning.
Market Snapshot and Core Challenges
The market’s expansion from 2020 to 2025 was marked by a resilient recovery pattern following broader chemical sector disruptions, with growth accelerating as pharmaceutical intermediate demand stabilized and specialty chemical supply chains adapted. The forecast window through 2032 suggests continued margin pressures alongside volume growth, as the addressable market broadens but competitive intensity increases. Concentration metrics indicate a moderately consolidated landscape, with the top three players capturing a notable share of supply and the top five firms controlling a majority of established distribution channels. This concentration does not imply uniform pricing power; instead, it reflects differentiated capabilities across purity grades, regional logistics, and application-specific technical support.
Several structural challenges define the current operating environment. First, feedstock price volatility introduces unpredictability into production economics. Bromine, a key input for the bromination steps required in manufacturing 2-cyanobenzyl bromide, has experienced fluctuating market prices, with recent indicators showing averages around USD 5,443 per metric ton FOB in early 2026 in China. For manufacturers operating on thin margins or serving price-sensitive segments, such volatility complicates cost planning, inventory strategy, and contract pricing. Second, regulatory and handling requirements add compliance overhead. The compound is classified under REACH Regulation (EC) No 1907/2006 with skin corrosion and irritation hazards, necessitating specific handling, storage, and documentation protocols. At the same time, its absence from the EPA Toxic Substances Control Act inventory in multiple supplier safety data sheets creates ambiguity for buyers operating in jurisdictions with stringent chemical registration or import requirements. This mixed regulatory visibility demands proactive compliance management rather than reactive adjustments. Third, application-specific expectations for purity and analytical verification are rising. Buyers in pharmaceutical and advanced research settings increasingly require detailed certificates of analysis, batch-level traceability, and documentation supporting NMR, HPLC, or GC purity claims. Suppliers that cannot provide consistent analytical data risk losing credibility in higher-value segments, even if their pricing is competitive.
These challenges are not isolated; they interact. Feedstock volatility affects margin stability, which in turn influences investment in quality control infrastructure. Regulatory complexity affects market access, which shapes regional demand patterns. Rising purity expectations affect supplier segmentation, which influences how consolidation or specialization unfolds. For decision-makers, the strategic question is not whether these pressures exist, but how to position operations and purchasing strategies to convert them into advantages rather than exposures.
Worldwide 2-Cyano-phenothiazine Market
Key Drivers of Market Change
Several interconnected drivers are shaping the trajectory of the 2-cyanobenzyl bromide market. Technological and process innovation remains a primary catalyst. Advances in bromination methodologies, purification protocols, and analytical verification have enabled producers to offer higher-purity grades with greater batch-to-batch consistency. This is particularly relevant for pharmaceutical intermediate applications, where purity thresholds and documentation standards directly affect downstream synthesis reliability. Manufacturers that have invested in high-purity production capabilities, supported by robust analytical data, are better positioned to serve API synthesis workflows and custom development projects. At the same time, research-grade suppliers have expanded catalog availability and bulk options, reducing lead times for laboratory and early-stage development work. The broader effect is a market where product grade, documentation quality, and technical support increasingly differentiate suppliers beyond baseline price competition.
Regulatory and compliance dynamics are also reshaping demand patterns. The REACH classification and associated handling requirements have elevated the importance of compliant packaging, safe storage guidance, and clear safety data sheet documentation. Buyers in Europe and other regulated markets are placing greater weight on suppliers who can demonstrate consistent compliance and transparent hazard communication. Simultaneously, the regulatory ambiguity around inventory listings in certain jurisdictions has prompted procurement teams to conduct more rigorous sourcing due diligence, particularly for companies scaling up from research quantities to pilot or commercial intermediate volumes. Compliance is no longer a back-office function; it has become a procurement criterion that can accelerate or delay sourcing decisions.
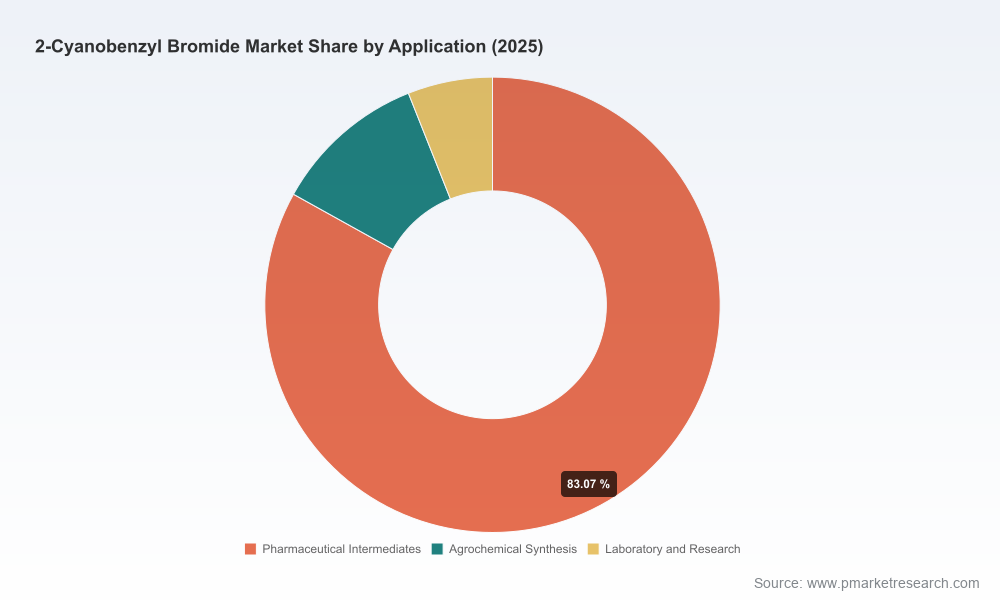
Demand-side shifts are equally significant. The pharmaceutical intermediates segment continues to be the largest demand pool, driven by ongoing synthesis needs for drug candidates and established API pathways. This demand is not uniform; it fluctuates with drug development cycles, generic entry timelines, and the pace of process optimization in manufacturing. Agrochemical synthesis represents a smaller but strategically important application pool, where intermediate demand is tied to formulation development and crop protection innovation cycles. Laboratory and research demand, while numerically smaller, plays an outsized role in early-stage discovery and custom synthesis, often serving as a leading indicator for future intermediate volume requirements when promising molecules advance toward development. Across these segments, the common trend is a preference for suppliers who can provide reliable supply, clear analytical documentation, and flexibility in order sizing.
Supply chain and cost structure changes are reinforcing these demand-side dynamics. Regional production concentrations have enabled certain suppliers to optimize logistics and reduce lead times for specific markets, while also exposing the broader supply base to localized feedstock and energy cost fluctuations. Procurement strategies are increasingly balancing price against reliability, with many buyers favoring suppliers that can offer consistent purity, documented quality systems, and responsive technical support over those competing solely on spot pricing. In this environment, cost structure resilience—achieved through feedstock planning, inventory buffering, and process efficiency—has become a competitive differentiator as much as absolute cost level.
Competitive Landscape and Leading Strategies
The competitive environment is shaped by a mix of established fine chemical manufacturers, regional producers, and global distributors, each pursuing distinct positioning strategies. Several Chinese manufacturers have built active supply capabilities for 2-cyanobenzyl bromide, targeting pharmaceutical and agrochemical intermediate markets with varying emphasis on purity grades and production capacity. Some of these producers have developed supply profiles that emphasize volume availability and intermediate-grade material for broader synthesis applications. Others have focused on higher-purity offerings, including material specifically positioned for pharmaceutical API synthesis workflows, with supporting analytical data such as HPLC verification. This divergence reflects a broader market pattern: competition is increasingly segmented by grade, documentation quality, and application fit rather than by a single price spectrum.
Japanese and global research-grade suppliers occupy a different strategic tier. One prominent Tokyo-based supplier with global operations, including distribution channels in North America, emphasizes research-grade material with certified purity levels and catalog availability, supplemented by bulk options for larger projects. This supplier’s positioning reflects an emphasis on reliability, purity consistency, and accessibility for laboratory and early-stage synthesis work. On the distributor side, large global chemical suppliers provide material for laboratory and research use, often with broad catalog reach and established logistics networks. Their value proposition centers on accessibility, standardized documentation, and the ability to serve fragmented research demand across multiple geographies. These distributors play a critical role in lowering barriers to sample-level and pilot-scale procurement, though they often compete on service and reach rather than on proprietary production advantages.
Indian manufacturers with global export capabilities and additional Chinese fine chemical producers further diversify the supply base. Some of these firms emphasize export-oriented supply, supported by quality documentation and the ability to serve international buyers seeking alternatives to regionally concentrated sources. Others highlight capacity scale and purity claims, such as 99 percent purity offerings with significant supply capacity, targeting buyers who need larger volumes for development or intermediate production. A subset of suppliers differentiates through analytical transparency, providing NMR, HPLC, and related data to support synthesis and quality verification. Collectively, these players illustrate a market where competitive advantage is increasingly tied to verifiable quality, application-specific positioning, and supply reliability, rather than to presence alone.
PW Consulting
The strategic positioning of leading players reveals several common themes. High-purity producers targeting pharmaceutical synthesis emphasize documentation, grade consistency, and alignment with API intermediate requirements. Research-grade suppliers emphasize accessibility, catalog breadth, and bulk flexibility. Regional manufacturers leverage production proximity and capacity scale to serve specific demand pools efficiently. Distributors leverage logistics and global reach to serve fragmented, lower-volume demand. This segmentation is not static. As demand matures and buyers become more selective, suppliers that can bridge multiple value drivers—purity, documentation, capacity, and responsiveness—tend to capture stronger positions. The market is also seeing subtle pressure toward consolidation in specific segments, as buyers prefer fewer, more reliable sources for critical intermediates, while simultaneously encouraging specialization, as niche players serve research, development, or application-specific needs that larger generalist suppliers may not prioritize.
Future Trends and Commercial Implications
Looking ahead to the 2026–2032 window, several trends are likely to shape commercial strategy. The first is the continued elevation of purity and documentation as baseline expectations rather than premium differentiators. As pharmaceutical and advanced synthesis workflows demand greater batch consistency and analytical transparency, suppliers that can reliably provide high-purity material with comprehensive certificates of analysis will be better positioned to retain and expand share in higher-value segments. This trend favors producers with mature quality systems and creates a barrier for suppliers whose documentation or analytical support remains inconsistent. Commercial implication: procurement teams should evaluate suppliers not only on price and lead time, but on the reliability of purity claims, the completeness of analytical data, and the supplier’s ability to support scale-up with consistent specifications.
Worldwide 4-Brombenzonitrile Market
The second trend is the growing importance of regulatory preparedness and hazard communication as procurement criteria. With REACH classification and handling requirements in force, and with regulatory inventory visibility varying across jurisdictions, buyers are likely to place greater weight on suppliers who can provide clear safety data sheets, compliant packaging, and consistent hazard communication. This does not necessarily restrict market growth, but it does shift sourcing decisions toward suppliers who reduce compliance risk and administrative burden. Commercial implication: organizations operating across multiple regulatory environments should build sourcing criteria that explicitly account for documentation quality, hazard classification clarity, and the supplier’s ability to support import or registration requirements where applicable.
The third trend is the interplay between feedstock cost volatility and supply chain resilience. Bromine price fluctuations, exemplified by recent market indicators in the mid-5,400 USD per metric ton range FOB in China, will continue to influence production economics and contract pricing. Suppliers with stronger feedstock planning, inventory management, and process efficiency are better positioned to stabilize pricing and maintain reliability through cost cycles. Buyers, in turn, may increasingly value long-term supply agreements or partnerships that reduce exposure to spot-market volatility, especially for intermediates that are critical to downstream timelines. Commercial implication: both suppliers and buyers should consider contractual and operational strategies that balance flexibility with predictability, particularly where intermediate supply is tied to development or production schedules with limited tolerance for disruption.
These trends carry inherent uncertainties. Demand for pharmaceutical intermediates is tied to drug development outcomes and generic competition cycles, which can shift procurement patterns faster than supply-side planning anticipates. Regulatory environments may evolve, particularly if inventory listing status or hazard classification expectations change in key markets. Feedstock markets can experience sudden price movements driven by regional supply constraints, energy costs, or trade dynamics. Any of these factors could alter the pace of growth or the distribution of value across market participants. The commercial opportunity lies in preparing for these uncertainties through diversified sourcing, robust quality systems, and clear application-based supplier evaluation rather than relying on a single price or supply point.
Strategic Recommendations for Decision-Makers
For manufacturers and suppliers, the priority is to align product grade, documentation, and capacity strategy with the segments that generate the most stable and valuable demand. High-purity production with verifiable analytical support should be treated as a core capability for pharmaceutical intermediate positioning, not as a peripheral service. At the same time, research-grade and catalog-accessible supply can serve as a reliable entry point for early-stage demand and broader visibility. Suppliers should also strengthen feedstock planning and cost resilience, since volatility in bromine pricing can quickly compress margins and disrupt pricing stability. Where possible, manufacturers should develop clear differentiation around grade consistency, documentation quality, and technical responsiveness, as these attributes increasingly influence supplier selection in higher-value workflows.
For investors and strategic planners, the market offers a profile of steady growth with segmented value capture. The opportunity is not simply in volume expansion, but in identifying suppliers and business models that can sustain margins through compliance readiness, analytical credibility, and supply reliability. Investment or partnership decisions should account for the extent to which a company is positioned across multiple demand pools, its ability to serve higher-purity or application-specific segments, and its resilience to feedstock and regulatory shifts. Concentration in the market suggests that scale and distribution reach provide advantages, but they do not guarantee superior economics unless paired with grade differentiation and compliance capability. A disciplined view of segment-specific value drivers will help avoid overgeneralizing from headline growth figures.
For procurement leaders and buyers, sourcing strategy should move beyond price-only comparisons toward a more holistic evaluation of reliability, purity assurance, documentation quality, and regulatory fit. The compound’s role as an intermediate means that supply disruptions or specification inconsistencies can cascade into downstream synthesis timelines, making supplier selection a risk management decision as much as a cost decision. Buyers should assess whether potential suppliers can provide consistent analytical data, clear safety documentation, and flexible order sizing that matches development or production needs. Where intermediate supply is critical to project timelines, establishing qualified backup sources and evaluating long-term supply arrangements can reduce exposure to spot-market volatility and unexpected compliance delays.
For organizations seeking a more detailed view of segment-level demand patterns, regional supply dynamics, purity-grade positioning, and supplier capability comparisons, the full research report provides the granular data and customized framework needed to translate these strategic themes into actionable sourcing, investment, and production decisions.
For detailed analysis of this topic, please visit the official page: Worldwide 2-Cyanobenzyl Bromide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
More Posts


Report This Post
Please complete the following requested information to flag this post and report abuse, or offensive content. Your report will be reviewed within 24 hours. We will take appropriate action as described in Findit terms of use.
