


Right Now

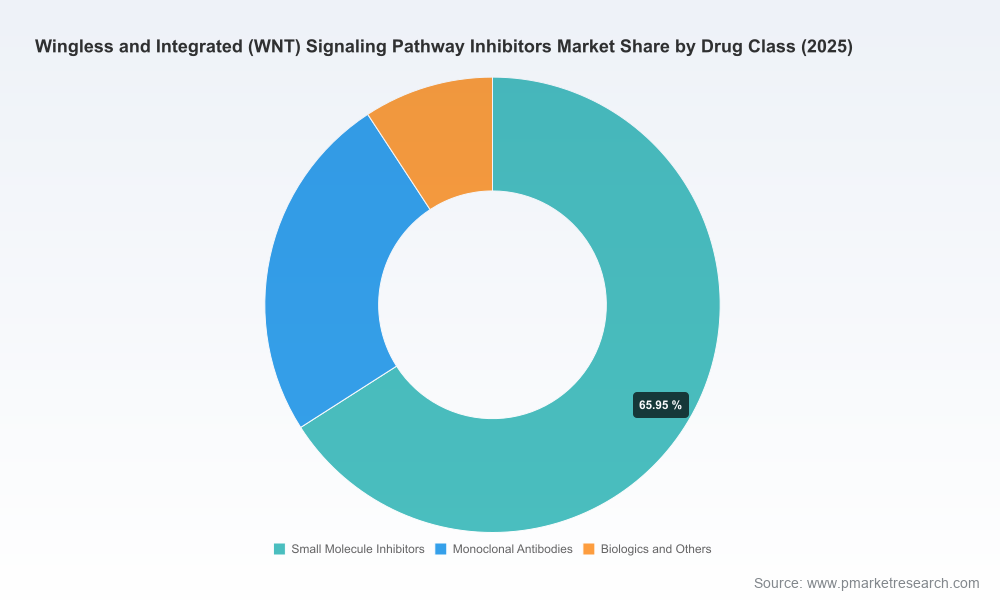
The WNT Signaling Pathway Inhibitors Market: Strategic Trends and Commercial Opportunities Through 2032
The WNT signaling pathway inhibitors market has entered a phase of structured acceleration, moving from a largely research-focused ecosystem toward clinical validation and eventual therapeutic deployment. Historical revenue growth from 2020 through 2025 demonstrates sustained demand expansion, with the market reaching a baseline of approximately $1.45 billion in the base year and maintaining momentum into the forecast period through 2032. The trajectory reflects a compound annual growth rate of 12.5%, a rate that signals more than incremental adoption; it points to structural shifts in how research institutions, biopharma companies, and specialty suppliers position WNT pathway modulation within their pipelines.
For executives and investors evaluating this space, the key question is no longer whether WNT inhibitors will gain relevance, but how the market will mature as early clinical programs progress and as manufacturing, regulatory, and reimbursement frameworks evolve. The commercial opportunity lies at the intersection of oncology precision therapy, fibrotic disease intervention, and the broader transition from research-grade reagents to clinically validated assets. Understanding where value is created, where bottlenecks persist, and how leading suppliers are differentiating is essential for strategic planning.
Market Landscape and Core Challenges
The market's growth story is anchored in consistent volume expansion across research applications, early-stage translational programs, and increasing interest from therapeutic developers exploring WNT pathway modulation. The revenue base has expanded steadily over the past several years, supported by growing procurement of pathway-selective inhibitors for target validation, preclinical models, and exploratory combination studies. Rather than a speculative phase, the market has reached a point where demand patterns are becoming more predictable, even as commercial outcomes remain contingent on clinical and regulatory developments.
Three challenges define the current inflection point. First, the absence of FDA-approved WNT signaling pathway inhibitors for therapeutic use creates a structural ceiling on commercial revenue until clinical programs demonstrate sufficient efficacy and safety. This means that today's market is still largely anchored in research use, with limited visibility into how quickly research-grade demand will convert into therapeutic-scale procurement. Decision-makers must balance near-term reagent and tool demand against longer-term pipeline risk.
Second, the market operates under labeling and usage constraints that explicitly restrict many WNT inhibitors to research applications, preventing diagnostic or therapeutic deployment in current commercial formats. This constraint shapes procurement behavior, pricing dynamics, and the pace at which suppliers can move from catalog-style distribution to more specialized, application-tailored offerings. It also influences how buyers assess supply reliability, purity standards, and technical support, since research outcomes depend heavily on reagent performance.
Third, complex multi-step synthesis for several inhibitor classes continues to pressure cost structures. Products targeting Porcupine and Tankyrase functions, for example, carry meaningful manufacturing complexity, with research-level pricing reflecting the technical demands of synthesis, purification, and quality control. As demand scales, suppliers that can streamline production, maintain consistent quality, and manage input volatility will gain a competitive advantage, while those reliant on fragmented or labor-intensive processes may face margin compression and supply risk.
Key Drivers Shaping Market Direction
Technology innovation remains a primary engine of demand. The availability of selective inhibitors across multiple node targets has expanded the experimental toolkit for academic labs, CROs, and biopharma discovery teams. Compounds that enable clearer dissection of WNT pathway behavior support target validation, mechanism-of-action studies, and combination strategy design. As research programs become more sophisticated, buyers increasingly prioritize reagents with well-characterized selectivity profiles, reliable batch consistency, and technical documentation that supports reproducible experimental outcomes. This shift favors suppliers that can pair product breadth with scientific credibility.
Regulatory and clinical context is reshaping expectations. Although no WNT signaling pathway inhibitor has yet received FDA approval for therapeutic use, the pipeline activity is substantial, with more than 100 active clinical trials targeting WNT pathway modulation, primarily in oncology. This volume of clinical exploration signals strong scientific conviction in the pathway's relevance, particularly in tumor biology and immune-oncology combination strategies. For commercial stakeholders, the implication is that today's research demand may be an early indicator of future therapeutic demand, provided clinical data support continued development. The timing and readability of clinical milestones will heavily influence downstream procurement patterns.
Demand-side behavior is also evolving. Research buyers are not simply purchasing individual inhibitors; they are assembling pathway-focused portfolios that enable comparative studies, dose-response modeling, and multi-target screening. This creates demand for curated catalogs, consistent supply continuity, and application-specific guidance. At the same time, biopharma and translational teams are increasingly interested in combination regimens, where WNT inhibition may be paired with chemotherapy or immuno-oncology agents. Early trial activity involving Porcupine inhibitors combined with gemcitabine and nab-paclitaxel in advanced pancreatic cancer, as well as combination studies with atezolizumab and bevacizumab in advanced solid tumors, illustrates how pathway inhibitors are being tested as enablers of broader therapeutic strategies rather than standalone solutions.
Cost and supply chain dynamics represent a fourth driver. As multi-step synthesis and quality requirements keep research quantities priced at meaningful levels, procurement teams are paying closer attention to supplier reliability, inventory depth, and the ability to support scaled research programs without disruption. Suppliers that invest in synthesis efficiency, analytical rigor, and responsive customer support can command stronger positioning, especially when buyers are building long-term experimental workflows or preclinical programs. In this environment, price alone is becoming less decisive than total value, which includes batch consistency, lead-time predictability, and technical expertise.
Competitive Landscape and Leadership Strategies
The supplier base is concentrated but diversified in positioning. Market concentration indicates that a relatively small group of players accounts for a meaningful share of activity, while several specialized companies compete on catalog breadth, product purity, and research-focused service models. Rather than competing solely on price, leading suppliers differentiate through portfolio relevance, scientific reputation, and the ability to support specific experimental needs.
MedChemExpress LLC has built a recognizable position by supplying research-grade WNT signaling pathway inhibitors across multiple target classes, including Tankyrase, Porcupine, and CBP-related modulators. Its strategy emphasizes breadth and accessibility, offering commonly referenced compounds that support a wide range of laboratory applications. This approach appeals to research teams seeking reliable access to established tools within a familiar procurement framework.
Selleck Chemicals similarly focuses on a research portfolio of pathway inhibitors, offering compounds that support mechanistic studies and screening workflows. Its differentiation sits in curated availability and product selection designed for experimental reproducibility. Cayman Chemical positions around high-purity inhibitors for laboratory research, targeting buyers who prioritize analytical quality and consistency for sensitive applications. Tocris Bioscience markets selective WNT pathway modulators and inhibitors, complementing inhibitor-focused lines with related tool compounds that support broader pathway investigation. Sigma-Aldrich leverages an extensive distribution footprint to make WNT inhibitors available through a broad chemical catalog, emphasizing reach and procurement convenience. TargetMol concentrates on a focused collection of inhibitors relevant to preclinical studies, including Porcupine and Tankyrase-targeting compounds, appealing to teams seeking specialized options for translational research.
PW Consulting
What distinguishes stronger performers is not simply catalog size, but the ability to reduce friction in research workflows. Suppliers that combine product availability with clear specifications, dependable shipping, and responsive technical guidance are better positioned to retain recurring research demand. In a market where many products remain research-labeled, trust in quality and consistency becomes a durable competitive asset.
The competitive landscape is likely to evolve along two complementary paths. One is consolidation among research-supply players seeking broader portfolios, wider distribution, and stronger technical support capabilities. The other is differentiation by application depth, where suppliers align more closely with specific use cases such as oncology target validation, fibrotic disease modeling, or bone and joint disorder research. New entrants may find opportunity not by replicating broad catalogs, but by offering specialized inhibitors, improved synthesis efficiency, or superior application support in areas where demand is intensifying.
Future Trends and Commercial Opportunities
Over the next three to five years, one of the most consequential trends will be the gradual shift from research-only demand toward clinical-stage commercial readiness. If ongoing trials continue to generate supportive data, the market will begin to anticipate therapeutic-scale requirements, including larger inventory commitments, more stringent quality expectations, and potentially different procurement models. Even before approval, positive clinical momentum can reshape buyer behavior, as developers secure supply for translational work and prepare for later-stage needs. Companies that can bridge research-grade availability with the operational discipline required for clinical-adjacent demand will be well placed.
A second trend is the growing importance of combination strategy enablement. WNT pathway inhibition is increasingly evaluated as part of broader regimens rather than as a solitary mechanism. This suggests that future demand may rise not only for inhibitors themselves, but for the research infrastructure needed to test combinations, measure pathway engagement, and interpret biomarker responses. Suppliers and service providers that can support combination-oriented workflows, whether through product portfolios, technical guidance, or complementary tools, may capture value beyond the immediate sale of individual compounds.
A third trend is cost and manufacturing competitiveness as a strategic differentiator. As demand expands, the companies that can manage synthesis complexity, stabilize supply, and maintain purity standards at scale will be better positioned to protect margins and win recurring procurement. This is especially relevant for inhibitor classes with challenging chemistry. Opportunities may arise for players that invest in process optimization, quality systems, and predictable lead times, because research and translational buyers increasingly value operational reliability alongside product selection.
These trends carry inherent uncertainty. Clinical outcomes remain the largest variable, and negative or ambiguous data in key oncology or fibrotic disease programs could slow the transition from research-focused procurement to therapeutic-scale demand. Regulatory and labeling constraints also continue to shape what can be commercially promised today. In addition, cost volatility, synthesis complexity, and supply continuity risk can affect pricing and availability, particularly if demand accelerates faster than manufacturing capacity. Strategists should therefore treat the market as high-potential but contingent, with value creation dependent on both scientific progress and operational execution.
Strategic Implications for Decision-Makers
For manufacturers and suppliers, the priority is to build durable advantage in quality, consistency, and workflow support rather than competing narrowly on catalog breadth or unit price. Investments in synthesis efficiency, analytical verification, and clear product documentation can strengthen repeat procurement and position a company for scaled demand if clinical momentum improves. It is equally important to prepare operating models for the possibility that research-labeled products may eventually sit within a more regulated or clinically adjacent context, where traceability, quality systems, and supply reliability carry greater weight. Companies should also monitor where demand is most likely to intensify, particularly in oncology and fibrotic disease applications, and align portfolio decisions accordingly.
Worldwide Vorinostat Market
For investors, the market offers a profile of strong structural growth paired with pipeline-dependent upside. The growth rate and expanding clinical trial activity suggest meaningful long-term potential, but near-term valuation and allocation decisions should account for the fact that therapeutic commercialization has not yet occurred. Due diligence should focus on supplier operating quality, synthesis and supply-chain resilience, portfolio relevance to high-value indications, and the ability to support recurring research demand while remaining capable of scaling if clinical outcomes improve. A disciplined approach recognizes that the most attractive opportunities may sit with companies that can convert scientific credibility into operational reliability and later-stage readiness.
For procurement and research leadership, the practical task is to secure supply resilience while maintaining scientific flexibility. This means evaluating suppliers not only on product availability, but on batch consistency, purity assurance, lead-time predictability, and technical support for complex applications. As research programs increasingly rely on pathway-focused tool sets and combination studies, procurement strategy should emphasize continuity, documentation, and vendor capability rather than transactional price optimization alone. Teams should also track clinical and regulatory developments closely, because changes in pipeline status can quickly shift demand expectations and preferred supply arrangements.
Worldwide Prostaglandins and Related Drugs Market
Given the pace of clinical activity, evolving regulatory context, and ongoing manufacturing complexity, the commercial picture is best understood through detailed segmentation, supplier-level benchmarking, and indication-specific demand scenarios. A comprehensive report can surface the granular data needed to evaluate where demand is strongest, how supplier positioning differs across segments, and which operational capabilities are likely to matter most as the market advances from research tools toward broader therapeutic relevance.
For detailed analysis of this topic, please visit the official page: Worldwide Wingless and Integrated (WNT) Signaling Pathway Inhibitors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
More Posts


Report This Post
Please complete the following requested information to flag this post and report abuse, or offensive content. Your report will be reviewed within 24 hours. We will take appropriate action as described in Findit terms of use.
