


Right Now

Strategic Trends and Commercial Opportunities in the Worldwide Embedded Hypervisor Software Market
The embedded hypervisor software market has entered a phase of rapid structural expansion, driven by the convergence of safety-critical system requirements, multi-OS workload consolidation, and hardware virtualization capabilities. Valued at 410.5 million USD in 2020, the market reached an estimated 565.0 million USD by 2025, reflecting a compound annual growth rate of 7.5 percent across the historical window. Projections through 2032 place the sector on a sustained upward trajectory, with annual revenue expected to approach 937.4 million USD by the forecast horizon endpoint. This growth is not uniform across all verticals or architectural approaches; rather, it is heavily concentrated in applications where deterministic real-time performance, mixed-criticality isolation, and regulatory compliance intersect. Understanding the mechanics behind this expansion requires moving beyond headline figures and examining the architectural, regulatory, and supply-chain forces shaping commercial adoption.
Market Snapshot
Embedded hypervisors function as thin, deterministic software layers that partition hardware resources among multiple operating environments within a single embedded controller or edge platform. The market’s growth to over 565 million USD in 2025 signals a transition from niche certification projects to mainstream platform strategy, particularly in sectors where safety certification, functional isolation, and lifecycle cost management dictate system architecture. The 7.5 percent CAGR reflects steady adoption rather than speculative hype, with revenue scaling as organizations consolidate legacy single-OS deployments into virtualized, multi-tenant embedded nodes. Concentration among established players remains pronounced, with the leading firms collectively accounting for more than half of total market revenue, while the top five entities capture nearly three-quarters of commercial activity. This concentration underscores a market defined by certification rigor, long development cycles, and deep integration with processor architectures, microcontroller ecosystems, and real-time operating environments. The revenue trajectory beyond the mid-2020s suggests compounding momentum, as initial platform decisions mature into fleet-wide deployments and as adjacent verticals adopt virtualization to meet evolving security, safety, and operational efficiency standards.
Core Challenges and Inflection Points
Despite robust top-line growth, the embedded hypervisor sector faces structural bottlenecks that determine which deployments succeed and which stall during qualification or integration phases.
The first inflection point stems from hardware dependency. Embedded hypervisors rely on specific processor extensions to deliver deterministic time and space partitioning without introducing unacceptable scheduling latency. Implementations targeting hard real-time workloads typically require ARM Cortex-R or Cortex-A cores equipped with ARMv8 virtualization extensions, or x86 platforms with VT-x capabilities. When hardware roadmaps diverge from hypervisor optimization timelines, or when legacy silicon lacks the necessary isolation primitives, organizations encounter costly re-architecture or face latency profiles that exceed real-time tolerances. This hardware-software alignment constraint is not merely a technical footnote; it shapes procurement cycles, supply-chain planning, and the speed at which new vertically integrated platforms can reach certification.
The second challenge lies in certification complexity and mixed-criticality compliance. Automotive system-on-chips that consolidate infotainment, powertrain control, and sensor fusion workloads, as well as avionics environments partitioning safety-critical flight functions alongside non-critical services, must satisfy stringent safety assurance levels. Automated compliance pathways are still maturing, and multi-domain partitioning increases the surface area that certification bodies must evaluate. Organizations deploying hypervisors in these environments navigate overlapping standards ecosystems, each with distinct documentation, testing, and traceability requirements. The convergence of multiple certification regimes can extend project timelines and increase engineering overhead, particularly when guest operating systems and hypervisor layers must be validated as an integrated safety case.
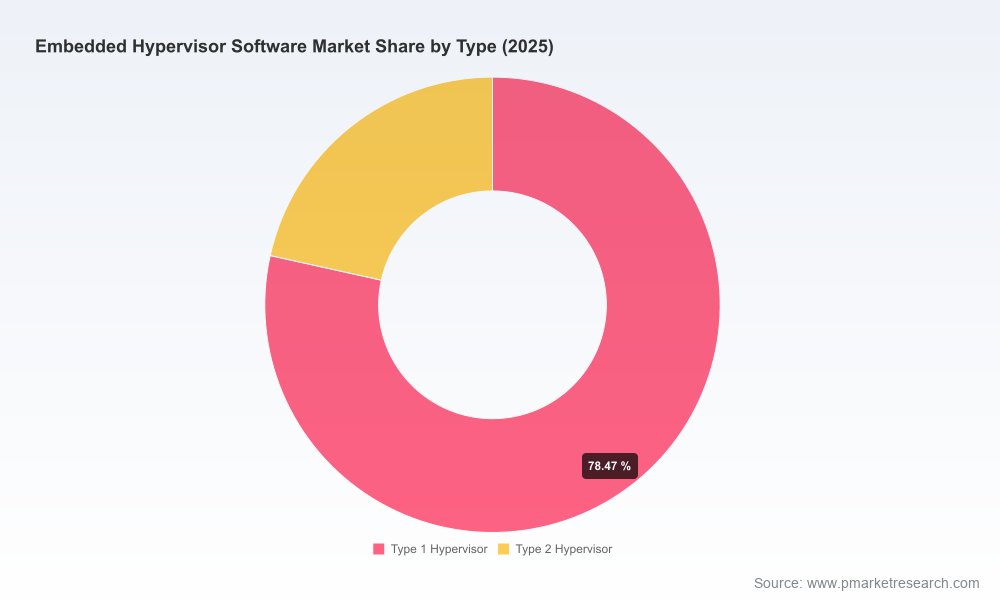
The third structural tension relates to architectural suitability. Type 2 hypervisors, which run atop a host operating system, remain useful in non-deterministic or general-purpose embedded scenarios, but they struggle in hard real-time contexts where host OS scheduling latency can exceed millisecond thresholds. In environments where deterministic response and fault isolation are non-negotiable, the market gravitates toward Type 1 implementations that provide direct hardware partitioning and separation-kernel guarantees. This architectural divide influences platform selection, supplier evaluation, and long-term maintainability, especially as embedded systems incorporate more concurrent workloads and more stringent security boundaries.
Together, these challenges define the current market inflection: organizations are moving from proof-of-concept virtualization toward production deployments, but only where hardware capabilities, certification strategies, and workload profiles align.
Key Demand Drivers
Technology Innovation and Architecture Evolution
Embedded virtualization is advancing along two parallel tracks: broader ISA support and tighter integration with safety and security architectures. Vendors have expanded support beyond traditional ARM and x86 targets to include emerging instruction sets, enabling hypervisor deployments on platforms designed for power efficiency and edge inference. Recent product iterations have reinforced this direction, with major releases extending embedded hypervisor capabilities to newer processor architectures and strengthening support for mixed-criticality workloads. This architectural broadening is not incremental; it allows OEMs and system integrators to reuse virtualization strategies across product families, reduce platform fragmentation, and plan multi-generation roadmaps around a common partitioning layer. As embedded systems increasingly combine real-time control, connectivity stacks, and localized AI processing, the hypervisor becomes a foundation for managing concurrency without sacrificing determinism.
Policy and Regulatory Environment
Regulatory frameworks continue to shape adoption patterns by defining what can be virtualized, how it must be partitioned, and which assurance levels must be demonstrated. In avionics, airworthiness standards require rigorous certification for hypervisors partitioning guest operating systems on commercial aircraft, reinforcing demand for solutions with documented traceability and partitioning guarantees. In automotive, safety standards mandate compliance for electronic control units handling mixed-criticality workloads, pushing suppliers to adopt virtualization only when they can prove isolation and failure containment across domains. Simultaneously, standardization efforts around time and space partitioning APIs provide a common interface model that reduces integration risk and improves portability across guest environments. The net effect is twofold: regulation raises the barrier to entry for low-assurance virtualization, while standardization lowers integration friction for certified solutions. This dynamic favors vendors with established certification artifacts and disciplined engineering processes, particularly in sectors where recall risk, airworthiness, or lifecycle liability is high.
Desktop Hypervisor Market
Demand-Side Shifts in Consumer and Enterprise Behavior
On the demand side, system architects are increasingly motivated by consolidation economics and functional agility. Rather than deploying multiple discrete controllers for distinct functions, organizations seek single-board or single-chip solutions that can host real-time control, connectivity, diagnostics, and non-critical user interfaces within a protected execution environment. This shift is visible in edge computing nodes, next-generation vehicle architectures, industrial controllers, and medical device platforms where software-defined functionality, over-the-air updates, and serviceability increasingly outweigh the cost of discrete hardware. At the same time, end-users and operators expect higher assurance that non-critical functions cannot compromise safety-critical operations, especially in environments where downtime, safety incidents, or regulatory scrutiny carry significant financial and reputational consequences. These expectations create durable demand for embedded hypervisors that can enforce domain isolation while simplifying system integration.
Supply-Chain and Cost-Structure Dynamics
Cost structures in embedded virtualization are being reshaped by vertical integration between silicon vendors and hypervisor suppliers. Partnerships that embed certified hypervisors directly into reference platforms reduce integration risk, shorten qualification cycles, and provide OEMs with clearer migration paths from development boards to production hardware. These collaborations help mitigate the hardware bottleneck by aligning processor roadmaps with hypervisor support, documentation, and reference implementations. At the same time, organizations are weighing the total cost of ownership across certification, toolchain licensing, long-term maintenance, and field support. In safety-critical verticals, the upfront cost of a certified hypervisor is often justified by reduced integration rework, faster regulatory approval, and lower risk of cross-domain faults in production. However, price sensitivity remains in cost-constrained industrial and consumer segments, where deterministic guarantees must be balanced against unit economics and deployment scale.
Embedded Systems Market
Competitive Landscape and Leading Strategies
The embedded hypervisor market is defined by a compact group of specialized vendors, each anchored in a distinct safety, certification, or architectural focus. Leadership is less about market share alone and more about the ability to deliver verifiable isolation, maintain certification continuity across domains, and align with hardware ecosystems that dominate target verticals.
Several vendors differentiate through domain-specific certification portfolios and separation-kernel architectures. Players with safety-critical heritage emphasize certification coverage across avionics, automotive, and industrial standards, positioning hypervisors as foundational components for mixed-criticality systems rather than optional add-ons. Others compete through real-time partitioning toolsets, multi-OS consolidation, and integration with AUTOSAR-oriented development flows. A number of suppliers align closely with silicon ecosystems, embedding their hypervisors into reference designs to streamline qualification and reduce time-to-deployment for industrial, aerospace, and automotive customers. In the automotive and medical segments, solutions with Type 1 virtualization and high-level safety certification continue to gain traction, particularly where edge compute modules must host both safety-related and non-safety-related workloads within a single platform. Toolchain providers contribute by combining hypervisor support with development environments and virtualization tooling, enabling engineers to debug, partition, and validate guest operating systems within a unified workflow. Automotive-focused engineering groups extend the competitive set by delivering hypervisors tailored to ECU consolidation, supporting standardization frameworks and safety compliance for networked embedded controllers.
Strategic positioning varies along several axes. One axis is certification depth: vendors that have invested in DO-178C, ISO 26262 ASIL D, IEC 61508, and related assurance artifacts often win in safety-critical procurement where qualification risk is a primary decision factor. A second axis is architecture compatibility: support for ARINC 653 partitioning, separation-kernel guarantees, and deterministic scheduling distinguishes solutions that serve avionics and defense applications from those targeting broader embedded use cases. A third axis is ecosystem alignment: partnerships with silicon vendors and reference platform availability can accelerate adoption by reducing integration uncertainty and providing validated deployment paths. Recent developments illustrate these strategies in action. Vendors have expanded hypervisor support for newer processor architectures and safety-critical use cases, broadened certification coverage into medical embedded environments, and formed partnerships that embed separation kernels into microcontroller series for industrial applications. In parallel, some suppliers have launched hypervisor versions optimized for automotive edge computing platforms, reinforcing the link between virtualization and next-generation embedded compute nodes.
The competitive landscape is evolving rather than fragmenting chaotically. Incumbents are strengthening vertical depth and certification continuity while selectively expanding into adjacent domains where assurance requirements align. Consolidation expectations remain elevated because qualification costs and long sales cycles favor vendors with sustained support commitments and documented safety cases. At the same time, new entrants face a steep path unless they bring differentiated hardware alignment, novel certification efficiency, or highly focused vertical expertise. Market share dynamics will likely continue to reward players who can reduce integration friction, maintain certification currency, and adapt to changing silicon roadmaps without breaking determinism or safety guarantees.
Future Trajectory and Commercial Opportunities
Looking ahead, three trends are likely to shape the embedded hypervisor market over the next three to five years.
First, mixed-criticality consolidation will accelerate as organizations push more functions onto fewer, more capable embedded platforms. The commercial opportunity lies in hypervisors that can isolate safety-critical control loops from connectivity stacks, diagnostics, and edge inference workloads while maintaining deterministic behavior and certifiable failure containment. Suppliers that demonstrate robust partitioning, predictable performance, and clear safety cases will capture demand from automotive ECU consolidation, industrial controller modernization, and avionics upgrade programs. The risk is that over-consolidation invites complexity that outpaces certification efficiency, particularly when guest operating systems, security stacks, and real-time tasks are combined without disciplined architecture.
Second, certification and assurance processes will become more standardized and more automated, lowering the effective cost of adopting virtualization in regulated domains. The opportunity here is for vendors and integrators who build reusable assurance artifacts, modular certification packages, and traceable partitioning models that can be adapted across product families. Standardization around partitioning APIs and safety case templates will help organizations scale deployments without restarting qualification from scratch for each variant. The uncertainty is that regulatory expectations may evolve faster than toolchain and process maturity, especially where new workload types, such as localized AI inference, intersect with existing safety frameworks.
Third, silicon-hypervisor co-design will deepen as processor vendors and hypervisor suppliers align reference platforms, virtualization extensions, and documentation to reduce integration risk. The commercial opportunity is in platforms that deliver validated partitioning out of the box, enabling faster migration from prototype to production and reducing the engineering burden on system integrators. Partnerships that lock in ecosystem alignment can create durable advantages in segments where procurement favors proven, supported roadmaps. The downside is dependency risk: if silicon roadmaps shift, certain hypervisor strategies may require re-validation or architectural adjustment, creating timing and cost uncertainty for long-lifecycle embedded programs.
These trends point to a market where the winners are not simply those offering virtualization, but those offering verifiable, maintainable, and ecosystem-aligned virtualization that reduces total program risk. Commercial upside is strongest where hypervisors enable functionality expansion without proportionally increasing hardware complexity or certification scope.
Strategic Guidance for Decision-Makers
For embedded system manufacturers and platform architects, the priority is to treat hypervisor selection as a long-term architecture decision rather than a short-term integration choice. Evaluate solutions based on determinism guarantees, certification coverage for the intended safety and compliance domain, hardware alignment, and the sustainability of the vendor’s certification and support roadmap. Prioritize platforms that offer reusable partitioning strategies and clear separation between safety-critical and non-critical workloads, especially when multi-generation product plans are in scope. Where possible, align procurement with reference platforms that reduce qualification ambiguity and accelerate validation.
PW Consulting
For investors and corporate development teams, the most defensible opportunities reside in vendors with deep certification portfolios, predictable release cadences, and strong ecosystem alignment with silicon and real-time operating environments. Vertical concentration in aerospace, defense, automotive, industrial automation, and medical devices suggests durable demand for assurance-driven virtualization, but growth will be uneven across segments and dependent on how quickly certification efficiency improves. Evaluate companies by their ability to maintain compliance currency, expand ISA support without compromising determinism, and sustain partnerships that shorten customer qualification cycles. Watch for consolidation signals, especially where certification overhead and long sales cycles create barriers that favor scaled incumbents.
For procurement and engineering leadership, the practical mandate is to reduce integration risk by mapping hypervisor adoption to clear workload boundaries and compliance requirements. Define partitioning policies early, document safety cases for mixed-criticality deployment, and avoid introducing virtualization where host-OS scheduling latency or certification scope would undermine real-time performance or regulatory acceptance. Where cost constraints are significant, compare total program cost rather than unit price alone, factoring in certification rework, integration effort, and lifecycle support. In safety-sensitive verticals, the cheapest implementation often becomes the most expensive if it triggers rework, delays certification, or introduces cross-domain fault risk.
The embedded hypervisor market is moving from specialized adoption toward broader platform strategy, but success depends on matching architectural capabilities with regulatory realities and hardware roadmaps. Detailed segmentation data, company-level revenue estimates, and vertical-specific adoption metrics can sharpen procurement, investment, and roadmap decisions beyond what aggregate trends reveal. Readers seeking deeper granularity on regional demand patterns, application-specific growth dynamics, and competitive positioning at the product level are encouraged to consult the full research report for comprehensive datasets and tailored strategic context.
For detailed analysis of this topic, please visit the official page: Worldwide Embedded Hypervisor Software Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
More Posts


Report This Post
Please complete the following requested information to flag this post and report abuse, or offensive content. Your report will be reviewed within 24 hours. We will take appropriate action as described in Findit terms of use.
