


Right Now

The Worldwide Burrito Forming Machine Market: Strategic Trends and Commercial Opportunities Through 2032
Market Overview: Scale, Momentum, and Structural Pressures
The global market for burrito forming machines has entered a sustained growth phase, expanding from approximately $312.45 million in 2020 to $421.68 million in 2025. Momentum is expected to continue through the forecast horizon, with revenues projected to reach $646.72 million by 2032. This expansion translates to a compound annual growth rate of 6.3 percent, reflecting a market that is moving beyond niche adoption into mainstream industrial food processing. The trajectory signals more than incremental demand; it indicates a structural shift in how manufacturers, commercial kitchens, and institutional caterers approach tortilla-based product assembly.
Several underlying dynamics explain this trajectory. Demand for standardized, high-throughput food assembly has intensified as frozen food portfolios expand, quick-service concepts scale, and institutional procurement seeks consistency across large batch runs. At the same time, equipment designers have responded with machines that integrate forming, folding, and rolling into unified workflows, reducing reliance on manual labor and improving product uniformity. The result is a market where capital equipment purchases are increasingly justified by operational efficiency, quality control, and throughput predictability rather than by volume requirements alone.
Despite the favorable macro direction, the industry faces a set of challenges that will shape how companies invest, compete, and capture value over the next several years.
- Execution risk in automation transitions. Moving from manual wrapping to automated forming is not a simple equipment swap. It requires changes in product specifications, tortilla thickness tolerances, line balancing, and operator training. Manufacturers that underestimate integration complexity can see delayed returns, higher changeover times, and inconsistent output.
- Cost and materials pressure. Food-grade equipment remains heavily dependent on stainless steel and precision components. As broader materials markets fluctuate, equipment manufacturers must manage input costs while maintaining hygiene standards, corrosion resistance, and regulatory compliance. Buyers, in turn, face capital expenditure decisions shaped by both machine pricing and total cost of ownership.
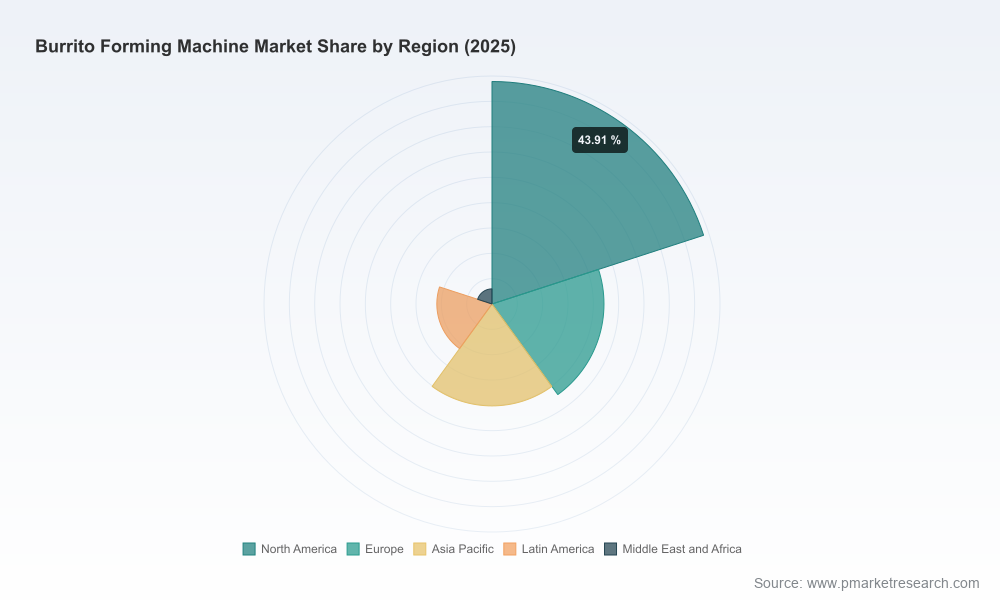
- Divergent regional maturity and demand profiles. The market is not uniformly ripe. Some regions already operate with established industrial food manufacturing ecosystems and high automation adoption, while others are in earlier stages of commercial food processing expansion. This uneven maturity affects everything from sales cycles and service networks to the relevance of certain machine configurations and support models.
For decision-makers, these challenges are not reasons to defer engagement. They are signals that equipment selection, deployment strategy, and supplier evaluation must be treated as operational decisions with multi-year consequences. The winners in this market will be those who understand not only what a machine can produce, but how it fits into throughput targets, labor models, quality systems, and regional food safety expectations.
Key Growth Drivers: Technology, Regulation, Demand, and Cost Structure
Technology Innovation and Capability Expansion
The most visible driver of market growth is the continued refinement of forming technology. Modern burrito forming machines increasingly combine automated filling, folding, and rolling in a single controlled process, enabling consistent output at commercial scale. High-capacity systems can support throughput levels suitable for large-scale frozen food production and high-volume service operations, while design variations address different tortilla formats and product sizes. Sensor-controlled operation, repetitive precision, and adjustable folding mechanisms are becoming central value propositions rather than peripheral features.
Worldwide Balloon Forming Machine Market
This technological progression matters because it changes the economics of production. A machine that delivers uniform portioning and repeatable folding reduces product variability, supports brand consistency, and lowers dependence on skilled manual wrapping. For manufacturers transitioning from manual processes, that shift can materially reduce labor intensity while improving line predictability. Technology leadership is therefore less about headline speed alone and more about achieving stable, repeatable output that matches the requirements of downstream packaging, freezing, and distribution.
Policy, Standards, and Export-Ready Compliance
Regulatory and standards environments are influencing purchasing decisions in subtle but important ways. Food equipment buyers increasingly expect machines that align with recognized quality and safety frameworks, especially when production spans multiple markets or when equipment must satisfy international procurement requirements. Certifications and compliance readiness can reduce friction in cross-border sales, simplify qualification processes for large food manufacturers, and strengthen confidence in long-term supplier reliability.
This is particularly relevant for suppliers targeting export growth. Machines designed with international standards in mind are better positioned to serve diverse customer bases without extensive revalidation or customization. In practice, compliance orientation is becoming a competitive differentiator because it supports scalability: an equipment platform that can be deployed across regions with minimal rework offers a clearer path to repeatable sales and service economies.
Demand-Side Shifts in Frozen Food, Quick Service, and Institutional Catering
Demand for burrito forming equipment is being reinforced by broader food sector trends. Frozen food manufacturers continue to expand 포트폴리오에 includes tortilla-based items that benefit from automated forming and consistent portion control. At the same time, fast food chains and restaurant operators are seeking production consistency, speed, and labor efficiency to support menu standardization and volume growth. Institutional and catering environments also value repeatable output when serving large groups where uniformity and food safety controls matter.
These demand-side shifts are not simply about more units sold. They reflect a preference for equipment that can support distinct operating models. A frozen food producer may prioritize high throughput, stable forming, and integration with downstream packaging, while a restaurant or catering operation may value flexibility, quicker changeovers, and compact footprint. As a result, machine suppliers that can align product capabilities with customer operating realities are better positioned to convert interest into installed bases.
Labor Economics and Total Cost of Ownership
Labor cost dynamics remain a significant force shaping adoption. For food manufacturers moving from manual wrapping to automated forming, the reduction in direct labor requirements can be substantial, altering the payback calculus for equipment purchases. Automation does not eliminate labor entirely, but it reallocates workforce needs toward supervision, maintenance, and quality oversight rather than repetitive hand assembly. That reallocation can improve consistency while helping operations manage wage pressure and staffing variability.
This driver is most powerful when analyzed as total cost of ownership rather than as upfront price. A forming machine may carry a higher initial capital outlay, yet deliver stronger returns through reduced labor exposure, fewer reject rates, and more predictable throughput. Buyers who evaluate only purchase price risk overlooking the operational value that automation can create over a multi-year horizon. Conversely, suppliers that can help customers model labor savings, changeover efficiency, and maintenance expectations are more likely to win considered purchases.
PW Consulting
Competitive Landscape: Positioning, Differentiation, and Market Evolution
The competitive environment is shaped by a mix of established equipment specialists and regional manufacturers with distinct technical and commercial positioning. Rather than competing solely on price, leading players tend to differentiate through throughput capability, integration flexibility, compliance readiness, and the ability to serve specific application profiles.
ANKO FOOD MACHINE CO., LTD. illustrates a strategy centered on controlled automation and international deployment. Its sensor-controlled burrito forming approach emphasizes automated filling, folding, and rolling with consistent output, and it supports thicker tortilla formats through modified folding mechanisms. Patented technology and a broad deployment footprint across many countries suggest a playbook built on proven performance, export orientation, and repeat installation experience. Participation in international food processing exhibitions further reflects a focus on visibility among commercial food manufacturers evaluating automation upgrades.
Solbern takes a more application-focused stance with burrito folding machines that aim for uniform finished output. Its broader dough folding portfolio, including solutions relevant to egg rolls and taquitos, points to a strategy that leverages shared forming and folding expertise across multiple product categories. For customers operating across related snack and appetizer lines, this multi-product relevance can be attractive because it supports equipment commonality and broader service relationships.
Daiei Engineering Co., Ltd. emphasizes higher throughput capacity and integration with wrapper baking equipment. Its burrito wrapping machine is designed for faster output and compatibility with crepe machines for wrapper baking, supporting an end-to-end production approach. This positions the company as a fit for operations that want to connect wrapper preparation and burrito assembly more closely, reducing manual handling and improving line continuity.
Formost Fuji Corporation contributes a packaging-oriented perspective through horizontal flow wrappers integrated into frozen burrito systems. Servo-driven quick changeovers and automatic product indexing highlight an emphasis on packaging performance, flexibility, and line efficiency. For frozen food manufacturers, this type of equipment can be critical because the forming step is only one part of a broader process that must also preserve product quality through wrapping and downstream handling.
Thermoforming Machines Market
Together, these profiles show that competition is fragmenting around customer use cases. Some suppliers compete on forming precision and throughput, others on multi-product folding versatility, others on integration with baking or packaging, and others on compliance and international deployment readiness. This diversification is healthy for buyers, but it also means that procurement teams must evaluate equipment against operational requirements rather than against a single set of specifications.
How the Landscape Is Evolving
Several trends are likely to reshape competition over the forecast period. First, differentiation will increasingly depend on integration maturity. As customers look to connect forming with downstream packaging and quality control, suppliers that can offer smoother line coordination and changeover efficiency will gain advantage. Second, international sales capability will matter more as exporting manufacturers seek equipment partners with proven cross-market support and standards alignment. Third, service, spare parts availability, and installation expertise will become more important as installed bases expand and customers focus on uptime and maintenance predictability.
There is also room for consolidation and for new entrants. Larger equipment groups may seek to broaden their automated food processing portfolios through acquisition or partnership, while smaller specialists may compete by targeting specific regional markets or niche application needs. The key question for the market is whether competition will settle around a few broad-platform providers or remain a mosaic of specialized players. The answer will depend on how strongly customers value integration breadth versus application-specific optimization.
Forward Outlook: Three Trends Shaping 2026 to 2032
Automation as the Baseline, Not the Exception
Over the next several years, automated burrito forming is likely to move from a productivity upgrade to an operational baseline in many commercial food environments. As labor availability and cost pressures persist, more manufacturers and large-scale food service operators will treat forming automation as a standard part of production planning. This does not mean every buyer will choose the same machine type, but it does suggest that manual-only workflows will become less common in higher-volume settings. The commercial opportunity lies in supporting this transition with equipment that is reliable, understandable, and adaptable to product variation.
Integration Across Forming, Packaging, and Quality Control
A second trend is deeper line integration. Buyers will increasingly evaluate forming machines not as standalone devices but as components within a broader production flow. That means more attention to compatibility with packaging equipment, indexing systems, changeover speed, and quality assurance workflows. Suppliers that can reduce friction between forming and downstream steps will be better positioned to win multi-equipment projects and long-term service relationships. The opportunity here is not simply to sell a machine, but to help customers build a more predictable and efficient production sequence.
Regional Expansion with Differentiated Go-to-Market Models
A third trend is regional divergence in adoption pathways. Mature markets may focus on modernization, line optimization, and replacement cycles, while faster-growing regions may see first-time automation adoption and new plant development. This will create different sales cycles, service requirements, and configuration preferences across geographies. Companies that can tailor their go-to-market approach to local operating conditions, food safety expectations, and procurement practices will be better placed to capture growth without over-relying on a single market.
These trends carry inherent uncertainties. Materials costs can affect equipment pricing and margin structures. Operational complexity can slow adoption if implementation support is weak. Regional demand may shift with economic conditions, food consumption patterns, and regulatory developments. In addition, the market may see changes in customer expectations around flexibility, sanitation, and traceability that could alter what counts as a competitive machine. The most resilient strategies will be those that assume continued growth while preparing for variability in how that growth is distributed across segments and regions.
Strategic Recommendations for Decision-Makers
For manufacturers evaluating production upgrades, the priority should be to match equipment capability to real operating requirements rather than to theoretical maximums. That means assessing tortilla specifications, throughput targets, changeover needs, and downstream packaging integration before selecting a forming system. A machine that performs well in a brochure but creates bottlenecks in a specific line configuration will underdeliver on its promise. Manufacturers should also treat implementation as a project with defined milestones for installation, training, and process validation, because execution quality often determines whether automation delivers its expected labor and consistency benefits.
For investors, the relevant question is where value is being created across the equipment chain. Growth in the burrito forming machine market is supported by broader demand for automated food assembly, but returns will depend on differentiation in integration, compliance, service, and regional reach. Companies that can prove repeatable deployment, strong uptime, and credible international support are better positioned than those competing primarily on headline specifications. Investors should also watch for signs of consolidation, service expansion, and platform broadening, since these can reshape competitive dynamics and customer lock-in.
For procurement and operations leaders, the focus should be on total cost of ownership and supplier credibility. evaluate not only forming capacity, but also sanitation design, maintenance access, parts availability, and the supplier's ability to support qualification and compliance requirements. Where production spans multiple sites or markets, compatibility and service consistency can matter more than marginal differences in machine speed. Procurement teams should also request operational references and implementation case examples that reflect their own production context, since performance can vary significantly across product formats and line configurations.
For a fuller understanding of how these trends break down across regions, machine types, applications, and competitive segments, the complete PW Consulting market research report provides a more detailed view of the data and strategic implications. The full analysis offers deeper segmentation context, company-level comparisons, and tailored guidance for different operating models, making it a practical reference for teams planning investments, procurement decisions, or market entry strategies in the burrito forming equipment space.
For detailed analysis of this topic, please visit the official page: Worldwide Burrito Forming Machine Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
More Posts


Report This Post
Please complete the following requested information to flag this post and report abuse, or offensive content. Your report will be reviewed within 24 hours. We will take appropriate action as described in Findit terms of use.
